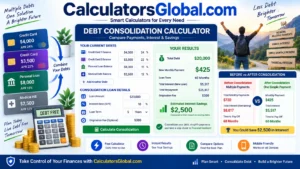
Debt Consolidation Calculator to estimate your new monthly payment, total interest, payoff time and potential savings when combining multiple debts.
A Debt Consolidation Calculator estimates the monthly payment, total interest, payoff period and potential savings when several debts are combined into one loan. To determine whether consolidation is financially beneficial, compare the new loan’s total cost, fees and repayment period with the total remaining cost of your existing debts. Credit Cards Payoff Calculator — Loan Calculator — Personal Loan Calculator — Interest Rate Calculator — EMI Calculator — Debt Payoff Calculator — Compound Interest Calculator — Percentage Calculator — Budget Calculator — Savings Calculator
Debt Consolidation Calculator: Compare Payments, Interest & Savings
Managing several debts at the same time can make personal finances difficult to understand. You may have multiple credit cards, a personal loan, a medical bill, an auto loan or other balances, each with a different interest rate and monthly payment.
A Debt Consolidation Calculator helps turn those separate debts into one easy-to-understand repayment scenario.
Instead of looking at each account separately, you can enter your outstanding balances, interest rates, fees and proposed consolidation-loan terms to estimate what your finances could look like after consolidation.
For example, imagine that you have:
- Credit Card 1: $4,000 at 24% APR
- Credit Card 2: $3,000 at 22% APR
- Personal Loan: $5,000 at 15% APR
Your total debt is:
$4,000 + $3,000 + $5,000 = $12,000
A consolidation calculator can help you compare this existing debt with a hypothetical consolidation loan.
Suppose the proposed loan has:
- Loan amount: $12,000
- APR: 10%
- Term: 4 years
The calculator can estimate the new monthly payment, total interest and total amount repaid.
However, a lower monthly payment does not automatically mean lower total cost. A consolidation loan may have a longer repayment period, origination fees or a promotional rate that later changes. The CFPB specifically recommends considering the loan term, fees, costs and whether a lower payment simply results from taking longer to repay the debt.
That is why a Debt Consolidation Calculator should be used to compare the complete cost of borrowing—not just the monthly payment.
What Is a Debt Consolidation Calculator?
A Debt Consolidation Calculator is a financial planning tool that helps you compare multiple existing debts with a potential consolidated loan or repayment plan.
Instead of calculating every debt separately, the calculator can combine the balances and estimate what a single repayment structure could look like.
Typical inputs include:
- Current debt balances
- Interest rates
- Minimum payments
- New consolidation-loan amount
- New interest rate
- Loan term
- Origination fees
- Other applicable costs
The calculator may then provide:
- Total existing debt
- New monthly payment
- Existing monthly payments
- Estimated total interest
- New-loan interest
- Total repayment
- Estimated interest savings
- Estimated monthly-payment savings
- Payoff period
What Does a Debt Consolidation Calculator Not Do?
A calculator does not approve a loan.
It does not guarantee:
- A particular interest rate
- Loan approval
- Credit-score improvement
- Interest savings
- Debt forgiveness
- A specific payoff date
The result depends on the assumptions you enter and the actual terms offered by a lender.
How Does a Debt Consolidation Calculator Work?
The calculator generally follows several steps.
Step 1: Add Your Existing Debts
Enter each debt separately.
For example:
| Debt | Balance | APR |
|---|---|---|
| Credit Card A | $4,000 | 24% |
| Credit Card B | $3,000 | 22% |
| Personal Loan | $5,000 | 15% |
Total debt:
$12,000
Step 2: Enter the New Loan Terms
Suppose the proposed consolidation loan has:
APR = 10%
Term = 48 months
Fee = $300
Step 3: Calculate the New Payment
The calculator uses the loan amount, interest rate and term to estimate the monthly payment.
Step 4: Calculate Total Cost
The calculator estimates:
Monthly Payment × Number of Payments + Applicable Fees
Step 5: Compare the Two Scenarios
You can compare:
Existing Debt Cost
versus
Consolidated Debt Cost
This comparison is more useful than looking only at the monthly payment.
What Is Debt Consolidation?
Debt consolidation means combining multiple debts into one debt or one repayment arrangement.
A debt consolidation loan is one common approach. You borrow money to repay multiple existing debts and then make payments on the new loan.
The CFPB describes a debt consolidation loan as borrowing money to repay separate debts so that you make one payment on the new loan.
Example
Before consolidation:
- Credit Card A
- Credit Card B
- Credit Card C
- Personal Loan
After consolidation:
- One consolidation loan
Instead of making four separate payments, you may have one monthly loan payment.
Does Consolidation Reduce Debt?
Not necessarily.
This is an important distinction.
Debt consolidation combines debt.
It does not automatically eliminate the amount you owe.
If you have:
$20,000 of debt
and consolidate it into one:
$20,000 loan
you still owe approximately $20,000, before applicable fees or other adjustments.
The potential benefit may come from:
- Lower interest
- Simplified payments
- Longer or shorter repayment term
- More predictable monthly payments
How Debt Consolidation Works
A simplified consolidation process looks like this:
Multiple Debts → Consolidation Loan → Existing Debts Paid → One New Payment
For example:
Before Consolidation
$5,000 Credit Card
$3,000 Credit Card
$7,000 Personal Loan
Total:
$15,000
After Consolidation
$15,000 Consolidation Loan
You then make one payment according to the new loan’s terms.
However, whether this is beneficial depends on the interest rate, term, fees and your ability to avoid taking on new debt.
The CFPB warns that taking on new debt to pay old debt may not solve the underlying problem if spending remains higher than income.
Debt Consolidation Formula
A debt consolidation calculator can use standard loan-amortization mathematics to estimate the payment on the new loan.
The basic monthly payment formula is:
PMT = P × r × (1 + r)ⁿ ÷ [(1 + r)ⁿ − 1]
Where:
- PMT = Monthly payment
- P = Loan principal
- r = Monthly interest rate
- n = Number of monthly payments
If the annual interest rate is 12%:
r = 12% ÷ 12 = 1%
As a decimal:
r = 0.01
If the loan term is 5 years:
n = 5 × 12 = 60
Important Assumption
This formula generally assumes:
- Fixed interest rate
- Fixed monthly payments
- No additional borrowing
- Regular monthly payment schedule
- No unexpected fees
Actual loan terms may differ.
Debt Consolidation Payment Formula
Suppose you consolidate:
$15,000
at:
10% APR
for:
5 years
Monthly rate:
10% ÷ 12 = 0.8333%
or approximately:
0.008333
Number of payments:
5 × 12 = 60
Using the standard payment formula gives an estimated monthly payment of approximately:
$318.71
Total scheduled payments:
$318.71 × 60 = $19,122.60
Approximate interest:
$19,122.60 − $15,000 = $4,122.60
This is a mathematical illustration and does not include lender fees.
Total Debt Calculation
Before comparing consolidation options, calculate your total outstanding debt.
The formula is simple:
Total Debt = Debt 1 + Debt 2 + Debt 3 + … + Debt n
Example:
| Debt | Balance |
|---|---|
| Credit Card A | $3,500 |
| Credit Card B | $2,500 |
| Personal Loan | $6,000 |
| Medical Debt | $1,000 |
Total:
$3,500 + $2,500 + $6,000 + $1,000 = $13,000
The $13,000 becomes the starting point for a consolidation comparison.
Average Interest Rate vs Weighted Average APR
Simply averaging APRs can produce a misleading result.
Suppose:
| Debt | Balance | APR |
|---|---|---|
| Debt A | $1,000 | 30% |
| Debt B | $9,000 | 10% |
A simple average is:
(30% + 10%) ÷ 2 = 20%
But Debt B is much larger.
A better measure for comparing the overall debt is a weighted average APR.
A simplified formula is:
Weighted Average APR = Σ(Balance × APR) ÷ Total Balance
For the example:
($1,000 × 30% + $9,000 × 10%) ÷ $10,000
= ($300 + $900) ÷ $10,000
= 12%
So the weighted average is approximately:
12%
rather than 20%.
Why This Matters
A debt consolidation calculator should compare the new loan’s APR with the actual cost of the existing debt, not just a simple average of interest rates.
Debt Consolidation Loan Example
Suppose you have:
| Debt | Balance | APR |
|---|---|---|
| Credit Card A | $5,000 | 25% |
| Credit Card B | $4,000 | 22% |
| Personal Loan | $6,000 | 14% |
Total debt:
$15,000
Now suppose you qualify for:
$15,000 consolidation loan
at:
11% APR
for:
60 months
The calculator can estimate the new payment and total interest.
The key question is:
Is the total cost of the new loan lower than the remaining cost of the existing debts?
If yes, consolidation may potentially reduce your overall cost.
If the new loan has a longer term or substantial fees, the answer may be different.
Debt Consolidation vs Existing Debt
A useful calculator should compare at least these figures:
| Metric | Existing Debt | Consolidation Loan |
|---|---|---|
| Total Balance | $15,000 | $15,000 |
| Interest Rate | Multiple | 11% |
| Monthly Payment | Multiple | One payment |
| Number of Payments | Multiple | 60 |
| Total Interest | Calculate | Calculate |
| Fees | Varies | Check lender |
| Total Cost | Calculate | Calculate |
The comparison helps you determine whether consolidation is actually improving the economics of the debt.
Monthly Payment Comparison
A lower monthly payment can be attractive.
For example:
Existing monthly payments: $600
New consolidation payment: $400
Monthly cash-flow reduction:
$600 − $400 = $200
That sounds beneficial.
But suppose the original debts would have been paid off in three years while the new loan lasts five years.
You may pay less each month but remain in debt longer.
The CFPB specifically warns that a lower monthly payment may result from extending the repayment period, potentially increasing the total amount paid.
Therefore, always compare:
Monthly Payment + Total Interest + Fees + Loan Term
rather than payment alone.
Interest Savings Calculation
A simplified interest-savings calculation is:
Interest Savings = Existing Debt Interest − Consolidation Loan Interest − Additional Fees
Suppose:
Existing interest = $8,000
New loan interest = $4,500
Fees = $500
Then:
$8,000 − $4,500 − $500 = $3,000
Estimated savings:
$3,000
This is an illustrative calculation.
Actual savings depend on the remaining balances, payment schedules, interest calculation methods and actual loan terms.
Debt Consolidation With Fees
Fees can significantly change the outcome.
Potential costs may include:
- Origination fees
- Balance-transfer fees
- Application fees
- Closing costs
- Prepayment penalties, where applicable
- Other lender charges
For example:
Loan amount = $20,000
Origination fee = 3%
Fee:
$20,000 × 3% = $600
If the fee is financed into the loan, the amount being repaid may be higher than $20,000.
This is why a debt consolidation calculator should include fees when possible.
Credit Card Debt Consolidation
Credit cards are among the most common debts considered for consolidation.
Suppose you have:
- $6,000 at 26%
- $4,000 at 23%
- $3,000 at 21%
Total:
$13,000
If you qualify for a consolidation loan at a lower fixed rate, the new loan may potentially reduce interest and simplify payments.
However, qualification depends on factors such as your credit profile, income and lender criteria.
The Biggest Risk
After paying off the cards, you may still have available credit.
If you use the cards again without changing your spending habits, you could end up with:
Consolidation Loan + New Credit Card Debt
The CFPB emphasizes that consolidation may not solve the underlying problem if spending continues to exceed income.
Personal Loan Debt Consolidation
A personal loan can be used to consolidate eligible debts.
Potential advantages include:
- One monthly payment
- Fixed repayment term
- Potentially lower APR
- Predictable payment schedule
Potential disadvantages include:
- Origination fees
- Longer repayment period
- Higher total cost in some cases
- Qualification requirements
- Possible variable or promotional terms
Always compare the full cost.
Balance Transfer Debt Consolidation
A balance transfer moves existing credit card debt to another credit card.
Some offers provide a promotional low or 0% APR for a limited period.
However, the CFPB warns that promotional rates generally last for a limited time and balance transfers commonly involve fees.
Example
Suppose:
Transferred balance = $10,000
Balance-transfer fee = 3%
Fee:
$10,000 × 3% = $300
If the promotional period is 18 months, you would need to repay a significant portion of the balance during that period to take full advantage of the promotional rate.
After the promotional period, the regular APR may apply.
Home Equity Debt Consolidation
Home equity can sometimes be used to consolidate debt through products such as:
- Home equity loans
- Home equity lines of credit
However, these products can use your home as collateral.
The FTC warns that some consolidation loans secured by a home can put the home at risk if payments are missed.
Therefore, a lower interest rate should not be the only consideration.
Debt Management Plan vs Debt Consolidation
These two concepts are often confused.
Debt Consolidation
You typically take out a new loan or use another financial product to combine debts.
Debt Management Plan
A credit counseling organization may help you create a repayment plan in which you make a payment and the organization distributes payments to creditors.
The CFPB explains that credit counseling organizations can help establish debt management plans and may sometimes negotiate lower interest rates or extended repayment terms, but they do not simply erase the debt.
Comparison
| Feature | Debt Consolidation Loan | Debt Management Plan |
|---|---|---|
| New loan | Usually yes | No |
| One payment | Often | Often |
| Credit counselor | Not required | Usually involved |
| Interest reduction | Depends on loan | May be negotiated |
| Debt eliminated | No | No |
| Fees | Lender-dependent | Counselor-dependent |
Debt Settlement vs Debt Consolidation
Debt settlement is different from debt consolidation.
Debt consolidation: Combines debts into a new payment structure.
Debt settlement: Attempts to negotiate a lower amount to settle a debt.
The FTC warns that debt settlement can involve significant risks, including late payments, additional fees and potential damage to credit if payments are stopped.
Never assume that an advertisement for “debt consolidation” actually describes a consolidation loan. Some companies may be offering debt settlement or another debt-relief service instead.
Debt Consolidation and Credit Score
Debt consolidation can affect your credit in several ways.
Hard Credit Inquiry
Applying for a new loan may result in a hard inquiry, depending on the lender and application process.
Credit Utilization
If credit card balances are paid off, your revolving utilization may change.
New Account
Opening a new loan creates a new account.
Payment History
Making payments on time is important for maintaining a healthy credit profile.
Important Point
Debt consolidation does not automatically increase your credit score.
The impact depends on your complete credit profile and what happens after consolidation.
If you consolidate credit card debt and then accumulate new balances, your financial position could become worse.
When Debt Consolidation May Make Sense
Debt consolidation may be worth considering when:
- You have multiple high-interest debts.
- You qualify for a meaningfully lower interest rate.
- The new loan has reasonable fees.
- The repayment term fits your budget.
- You want to simplify multiple payments.
- You have a clear plan to avoid new debt.
- The total cost is lower than keeping the existing debts.
A Good Consolidation Scenario
Suppose:
Existing debt: $20,000
Estimated remaining interest: $8,000
New loan interest: $5,000
Fees: $500
Potential savings:
$8,000 − $5,000 − $500 = $2,500
This could be a potentially favorable scenario.
When Debt Consolidation May Not Make Sense
Consolidation may not be beneficial when:
- The new APR is similar or higher.
- Fees are excessive.
- The new loan has a much longer term.
- You are using consolidation to continue borrowing.
- You are putting an important asset at unnecessary risk.
- The monthly payment is lower only because the loan lasts much longer.
- You cannot afford the new payment.
- The offer has a temporary promotional rate that later increases.
The CFPB recommends examining teaser rates, fees, repayment duration and total costs before taking out a consolidation loan.
How to Use a Debt Consolidation Calculator
Using a Debt Consolidation Calculator is straightforward.
Step 1: List Your Debts
Collect:
- Current balance
- APR
- Minimum payment
- Remaining term, if applicable
Step 2: Enter Each Balance
Example:
Credit Card A = $4,000
Credit Card B = $3,000
Personal Loan = $8,000
Step 3: Calculate Total Debt
The calculator adds the balances.
$4,000 + $3,000 + $8,000 = $15,000
Step 4: Enter the Proposed Consolidation Loan
For example:
Loan amount = $15,000
APR = 10%
Term = 48 months
Step 5: Enter Fees
If the lender charges a 3% origination fee:
$15,000 × 3% = $450
Step 6: Calculate
The calculator estimates the new payment and total cost.
Step 7: Compare Results
Look at:
- Existing monthly payments
- New monthly payment
- Existing interest
- New interest
- Fees
- Total cost
- Payoff period
Real-Life Debt Consolidation Examples
Example 1: $10,000 of Credit Card Debt
Suppose:
| Card | Balance | APR |
|---|---|---|
| Card A | $4,000 | 25% |
| Card B | $3,500 | 23% |
| Card C | $2,500 | 21% |
Total:
$10,000
Now suppose a consolidation loan is offered at:
12% APR
for:
48 months
The calculator can estimate whether the lower rate offsets any fees and the new repayment term.
Example 2: $20,000 of Mixed Debt
Suppose:
| Debt | Balance | APR |
|---|---|---|
| Credit Card | $8,000 | 26% |
| Credit Card | $5,000 | 24% |
| Personal Loan | $7,000 | 15% |
Total:
$20,000
Potential consolidation loan:
$20,000 at 11% for 60 months
A calculator can compare the two scenarios.
Example 3: $30,000 of Debt
Suppose:
Total debt = $30,000
Potential consolidation loan:
APR = 10%
Term = 60 months
The calculator can estimate the payment and total interest.
But before accepting the offer, compare:
New loan cost + fees
against:
Remaining cost of current debts
$10,000 Debt Consolidation Example
Suppose you consolidate:
$10,000
at:
10% APR
for:
48 months
Using the standard amortization formula gives an estimated monthly payment of approximately:
$253.63
Estimated total payments:
$253.63 × 48 = $12,174.24
Estimated interest:
$12,174.24 − $10,000 = $2,174.24
This is a mathematical example before fees.
$20,000 Debt Consolidation Example
Suppose:
Loan = $20,000
APR = 10%
Term = 60 months
Estimated monthly payment:
Approximately $424.26
Estimated total payments:
Approximately $25,455.60
Estimated interest:
Approximately $5,455.60
Again, this assumes a fixed-rate installment loan with regular monthly payments and no additional fees.
$30,000 Debt Consolidation Example
Suppose:
Loan = $30,000
APR = 9%
Term = 60 months
Estimated monthly payment:
Approximately $622.75
Estimated total payments:
Approximately $37,365
Estimated interest:
Approximately $7,365
These examples are for illustration and should not be interpreted as actual loan offers.
Debt Consolidation Comparison Table
| Factor | Existing Debts | Consolidation Loan |
|---|---|---|
| Number of payments | Multiple | Usually one |
| Interest rates | Often multiple | Usually one |
| Monthly payment | Multiple payments | One payment |
| Loan term | Varies | Fixed or specified |
| Fees | Existing-account dependent | May include new fees |
| Total interest | Calculate | Calculate |
| Convenience | Lower | Higher |
| New borrowing | No | Yes |
| Credit impact | Existing accounts | New account/inquiry possible |
Debt Consolidation vs Balance Transfer
| Feature | Consolidation Loan | Balance Transfer |
|---|---|---|
| Product | Installment loan | Credit card |
| Payment | Usually fixed | Credit-card payment |
| Promotional rate | Possible | Common |
| Transfer fee | Possible | Common |
| Term | Fixed | Promotional period + ongoing terms |
| Risk | Longer term/fees | Promotional rate expiration |
| Best comparison | Total loan cost | Fee + promotional period + regular APR |
Debt Consolidation vs Debt Avalanche
These are different concepts.
A debt consolidation loan changes the structure of your debt.
A debt avalanche changes the order in which you repay existing debts.
You can potentially use an avalanche strategy without taking a new loan.
For example, if you have:
- 25% APR credit card
- 20% APR credit card
- 15% APR personal loan
you can direct extra payments toward the 25% debt first.
Debt Consolidation vs Debt Snowball
The snowball method focuses on the smallest balance.
For example:
| Debt | Balance |
|---|---|
| Card A | $500 |
| Card B | $2,000 |
| Card C | $6,000 |
The snowball method would prioritize Card A.
This can help create psychological momentum without taking out a new loan.
Common Debt Consolidation Mistakes
Mistake 1: Looking Only at the Monthly Payment
A lower monthly payment can hide a longer repayment period.
Mistake 2: Ignoring Fees
Origination and transfer fees can reduce or eliminate potential savings.
Mistake 3: Ignoring the Loan Term
A 7-year loan may have a lower payment than a 3-year loan but can cost more in total interest.
Mistake 4: Accepting a Promotional Rate Without Reading the Terms
A low introductory rate may not last forever.
Mistake 5: Using Home Equity Without Understanding the Risk
A secured loan can put your property at risk if you cannot repay it.
Mistake 6: Consolidating and Then Reusing Credit Cards
This can result in new debt on top of the consolidation loan.
Mistake 7: Believing Debt Consolidation Means Debt Forgiveness
Consolidation generally restructures debt rather than eliminating it.
Mistake 8: Paying an Upfront Fee to a Debt Relief Company
The FTC warns that upfront-fee demands and guaranteed debt-relief promises are major warning signs.
How to Get the Most From Debt Consolidation
Compare Multiple Offers
Do not automatically accept the first offer.
Compare:
- APR
- Fees
- Term
- Monthly payment
- Total repayment
- Prepayment terms
Calculate Total Cost
Always calculate:
Total Payments + Fees
rather than comparing monthly payments alone.
Keep the New Loan Short When Affordable
A shorter term can reduce total interest, although it usually increases the monthly payment.
Avoid New High-Interest Debt
If you consolidate credit cards, consider how you will prevent the balances from building again.
Create a Budget
A consolidation loan works best when paired with a sustainable spending plan.
Track Your Progress
Monitor:
- Remaining balance
- Interest paid
- Monthly payment
- Payoff date
Debt Consolidation Scams and Warning Signs
Debt can make people vulnerable to aggressive financial marketing.
The FTC’s current consumer guidance warns consumers about debt-relief scams, including companies that promise quick debt forgiveness or demand payment before providing legitimate assistance.
Warning Signs
Be cautious when a company:
- Guarantees debt forgiveness
- Promises to settle all debts
- Demands payment upfront
- Claims to have a special government program
- Pressures you to act immediately
- Tells you to stop communicating with creditors without clearly explaining consequences
- Requests sensitive financial information unexpectedly
The FTC states that legitimate debt-relief assistance should not require consumers to pay upfront before the promised service has been provided.
Debt Consolidation Is Not the Same as Debt Settlement
This distinction is important.
A consolidation loan generally pays off existing debts with borrowed money.
Debt settlement involves negotiating with creditors to settle debts for less than the amount owed.
The risks and consequences are different.
Frequently Asked Questions
What is a Debt Consolidation Calculator?
A Debt Consolidation Calculator estimates the payment, interest and total cost of combining multiple debts into a single loan or repayment structure.
How does debt consolidation work?
A consolidation loan can be used to pay off several existing debts, leaving you with one new loan and one scheduled payment.
Does debt consolidation reduce my debt?
Usually, no. Consolidation combines or restructures debt. You still generally owe the principal balance plus applicable interest and fees.
Does debt consolidation save money?
It can, but not always. Savings depend on the new interest rate, fees, loan term and remaining cost of your existing debts.
Is a lower monthly payment always better?
No. A lower payment may result from extending the loan over a longer period, which can increase total interest. The CFPB specifically recommends comparing the total cost rather than focusing only on the monthly payment.
What is the best debt consolidation loan?
There is no single best loan for everyone. Compare APR, fees, term, monthly payment, total repayment and eligibility requirements.
Can I consolidate credit card debt?
Yes, depending on the product and lender. Common approaches include personal consolidation loans and balance transfers.
Can I consolidate multiple credit cards into one payment?
Yes. A consolidation loan or balance-transfer product may allow multiple credit card balances to be combined into one payment structure.
What credit score do I need for debt consolidation?
There is no universal minimum. Lenders set their own eligibility criteria, and the interest rate offered can depend on credit history and other factors.
Does debt consolidation hurt your credit score?
Applying for a new loan may result in a hard inquiry, and opening a new account can affect your credit profile. Over time, the impact depends on your payment history, balances and overall credit profile.
Is debt consolidation better than a balance transfer?
It depends. A balance transfer may provide a promotional low APR, while a consolidation loan may provide a fixed rate and fixed term. Compare fees, promotional periods, regular APR and total repayment cost.
Is debt consolidation better than debt settlement?
They are different strategies. Consolidation generally restructures debt into a new loan, while settlement involves negotiating to pay less than the amount owed. Settlement can have significant credit and financial consequences.
Can I consolidate debt with bad credit?
Some lenders offer consolidation products to borrowers with lower credit scores, but rates may be higher and loan terms may be less favorable.
Can I use a personal loan to consolidate debt?
Yes, personal loans are commonly used for debt consolidation.
Can I consolidate medical debt?
Potentially, depending on the lender and loan terms. Before converting potentially low-cost or interest-free medical debt into an interest-bearing loan, compare the total costs carefully.
Can I consolidate an auto loan?
Some lenders may allow certain types of debt to be consolidated, but eligibility depends on the lender and loan product.
Can I consolidate student loans?
Student-loan consolidation has specific rules and can be different from a general debt consolidation loan. Federal student-loan borrowers should review official government guidance before refinancing or consolidating.
What is a weighted average interest rate?
A weighted average APR accounts for the size of each debt. A large debt with a high APR has more influence than a small debt with a high APR.
How do I calculate debt consolidation savings?
A simplified formula is:
Savings = Existing Remaining Interest − New Loan Interest − Fees
The result should be based on actual remaining balances and realistic loan terms.
What fees should I consider?
Depending on the product, fees may include:
- Origination fees
- Balance-transfer fees
- Closing costs
- Administrative fees
- Other lender charges
Can debt consolidation lower my monthly payment?
It can, especially if the new loan has a lower interest rate or longer repayment term. But a lower payment does not necessarily mean a lower total cost.
How long should a debt consolidation loan be?
The ideal term depends on your budget and total cost. A shorter term generally means higher monthly payments but can reduce total interest.
Should I close my credit cards after consolidation?
Not necessarily. Closing accounts can affect your available credit and credit utilization. Consider your individual situation and whether you can avoid accumulating new balances.
What happens if I use my credit cards again after consolidation?
You could end up with both the consolidation loan and new credit card balances, increasing your total debt.
Is debt consolidation a good idea?
It can be useful when it genuinely lowers the overall cost or makes repayment more manageable without creating new financial problems. It is not automatically the right choice for everyone.
How can I avoid debt consolidation scams?
Avoid companies that guarantee debt forgiveness, pressure you to act quickly, demand suspicious upfront fees or make unexpected offers to “fix” your debt. The FTC recommends carefully researching debt-relief providers and being cautious about promises that sound too good to be true.
Should I talk to a credit counselor?
If you are unsure which repayment option fits your situation, a reputable nonprofit credit counselor may help you review your budget and repayment options. The CFPB notes that credit counseling organizations can help consumers create debt-management plans.
Important Debt Consolidation Calculator Disclaimer
The CalculatorsGlobal.com Debt Consolidation Calculator provides estimates for educational and financial-planning purposes.
Actual loan payments, interest costs and savings can differ because lenders may use different interest calculations, fees, loan terms, eligibility requirements and other conditions.
A lower monthly payment does not necessarily mean a lower total cost.
Before accepting a debt consolidation loan, review the lender’s complete disclosure, APR, fees, repayment period, total payments and other terms.
This calculator does not provide financial, legal, tax or credit advice and does not guarantee loan approval or savings.
Conclusion
A Debt Consolidation Calculator can help you answer one of the most important questions when considering consolidation:
Will combining my debts actually make repayment cheaper or easier?
The answer should not be based only on the monthly payment.
A useful comparison should consider:
- Total debt
- Existing interest rates
- New APR
- Monthly payment
- Loan term
- Origination or transfer fees
- Total interest
- Total amount repaid
- Payoff date
For example, a new loan can reduce a monthly payment from $700 to $450, but if the repayment period increases substantially, you could pay more interest overall.
The CFPB recommends looking beyond the headline payment and considering promotional rates, fees, loan duration and total costs before consolidating debt.
Debt consolidation can also work best when it is combined with a realistic budget and a plan to avoid rebuilding high-interest debt.
If your debt situation is difficult, consider speaking directly with your creditors or a reputable nonprofit credit counselor. Be particularly cautious about debt-relief companies that promise guaranteed results or demand payment before providing legitimate assistance. The FTC’s current guidance highlights these as important warning signs.
Use the CalculatorsGlobal.com Debt Consolidation Calculator to compare your current debt with a potential consolidation loan and understand your estimated monthly payment, interest cost, repayment period and potential savings.