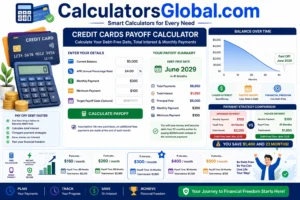
Credit Cards Payoff Calculator to estimate payoff time, monthly payments, total interest, and savings from paying off credit card debt faster. Debt-to-Income Ratio Calculator – Personal Loan Calculator – Loan Payment Calculator – EMI Calculator – Simple Interest Calculator Compound Interest Calculator – Percentage Calculator – Budget Calculator – Savings Calculator – Investment Calculator. A Credit Cards Payoff Calculator estimates how long it will take to eliminate credit card debt based on your current balance, APR, monthly payment and other factors. It can also estimate total interest and show how increasing your monthly payment may help you become debt-free sooner.
Credit Cards Payoff Calculator: Calculate Your Debt-Free Date, Interest & Monthly Payments
Credit card debt can become expensive when balances remain unpaid from month to month. Even a relatively small balance can take years to repay if you make only minimum payments while interest continues to accumulate.
A Credit Cards Payoff Calculator helps you understand exactly how your payment strategy can affect your debt. Instead of guessing how long it will take to become debt-free, you can estimate:
- How many months it may take to pay off your credit card
- Your estimated debt-free date
- Total interest paid
- Total amount paid
- Monthly payment required to reach a target payoff date
- How much interest you could potentially save by paying more
- The difference between minimum payments and fixed payments
- How different interest rates affect your repayment period
For example, imagine you have a $5,000 credit card balance with a 24% annual percentage rate (APR). Paying only a small minimum payment can result in substantial interest charges and a long repayment period.
Increasing your monthly payment can potentially shorten the payoff period and reduce the total interest you pay.
What Is a Credit Cards Payoff Calculator?
A Credit Cards Payoff Calculator is an online financial tool that estimates how long it may take to pay off credit card debt and how much interest you may pay during the repayment period.
The calculator typically uses:
- Current credit card balance
- Annual percentage rate (APR)
- Monthly payment
- Minimum payment
- Desired payoff period
- Additional monthly payment
- Number of credit cards, if supported
Depending on the calculator, the results may include:
- Estimated months to payoff
- Estimated payoff date
- Total interest
- Total payments
- Interest savings
- Monthly payment required
- Comparison between different repayment strategies
Why Is a Credit Card Payoff Calculator Useful?
Credit card debt is easier to manage when you know the numbers.
For example, you may think:
“I can afford to pay $250 per month, so I should be debt-free fairly soon.”
But the actual payoff period depends on your balance and interest rate.
A calculator lets you see whether $250 per month is enough to meet your target.
How Does a Credit Card Payoff Calculator Work?
A credit card payoff calculator uses the balance, interest rate and payment amount to simulate how the balance changes over time.
A simplified monthly calculation works like this:
Monthly Interest = Current Balance × Monthly Interest Rate
Then:
New Balance = Current Balance + Interest − Payment
The calculation repeats every month until the balance reaches zero.
Example
Suppose:
- Balance = $3,000
- APR = 24%
- Monthly payment = $150
A simplified monthly interest rate is:
24% ÷ 12 = 2%
First month’s interest:
$3,000 × 2% = $60
If you pay $150:
$3,000 + $60 − $150 = $2,910
The next month’s interest is calculated on the new balance.
As the balance falls, the interest charge also falls, assuming the APR remains unchanged and there are no new purchases or fees.
Why Credit Card Debt Can Be Expensive
Credit cards can carry relatively high interest rates compared with some other forms of borrowing.
The biggest problem occurs when a cardholder carries a balance for a long period.
Consider the following simplified example:
Balance = $5,000
APR = 24%
At 24% APR, the nominal monthly rate used for a simplified calculation is:
24% ÷ 12 = 2%
An initial balance of $5,000 would therefore generate approximately:
$5,000 × 2% = $100
of interest for one month under this simplified assumption.
If your payment is only slightly higher than the interest charge, the principal balance may decline slowly.
This is why understanding the relationship between APR, balance and monthly payment is important.
Credit Card Payoff Formula
A common fixed-payment formula is based on the standard loan amortization equation.
The number of monthly payments can be estimated using:
n = −ln(1 − (r × B ÷ P)) ÷ ln(1 + r)
Where:
- n = number of months
- B = current balance
- r = monthly interest rate
- P = monthly payment
If APR is expressed as a percentage:
r = APR ÷ 12 ÷ 100
Important Limitation
This formula assumes:
- A constant interest rate
- A fixed monthly payment
- No new purchases
- No additional fees
- Regular monthly compounding
- No changes to the account
Actual credit card calculations can differ because issuers may calculate interest using daily periodic rates, average daily balances, fees, promotional APRs and other account-specific rules.
Therefore, a calculator should be treated as an estimate.
Credit Card Interest Formula
A simplified interest calculation is:
Interest = Balance × Monthly Rate
For example:
Balance = $4,000
APR = 18%
Monthly rate:
18% ÷ 12 = 1.5%
Monthly interest:
$4,000 × 1.5% = $60
If you make a $200 payment:
$200 − $60 = $140
approximately goes toward reducing the principal under this simplified example.
The actual credit card statement can use a different calculation method.
How Credit Card APR Works
APR stands for Annual Percentage Rate.
It represents the annualized cost of borrowing, expressed as a percentage.
For example:
- 12% APR
- 18% APR
- 24% APR
- 29.99% APR
A higher APR generally means more interest charges when you carry a balance.
APR Does Not Mean You Pay the APR Once a Year
If you carry a balance, interest is generally calculated periodically rather than simply charging the entire annual percentage once at the end of the year.
Credit card issuers can use daily periodic rates and other methods described in the card agreement.
This is why using the actual APR and account terms is important when estimating payoff time.
APR vs Monthly Interest Rate
For a simplified nominal conversion:
Monthly Rate = APR ÷ 12
For example:
| APR | Approx. Monthly Rate |
|---|---|
| 12% | 1.00% |
| 18% | 1.50% |
| 20% | 1.67% |
| 24% | 2.00% |
| 27% | 2.25% |
| 30% | 2.50% |
These are simplified conversions and should not be interpreted as the exact periodic rate used by every credit card issuer.
Minimum Credit Card Payment
Credit card companies generally require a minimum payment each billing cycle.
The minimum payment can be calculated according to the card issuer’s terms and may involve:
- A percentage of the balance
- Interest and fees
- A minimum fixed dollar amount
- Certain other account-specific rules
Paying only the minimum can result in a long repayment period when the balance is large and the APR is high.
Why Minimum Payments Can Be Problematic
Suppose:
Balance = $6,000
APR = 25%
If the required minimum payment is relatively small, a significant part of the payment may initially go toward interest rather than principal.
The balance can therefore decline slowly.
A Credit Cards Payoff Calculator allows you to compare the minimum payment with a larger fixed payment.
How Long Does It Take to Pay Off a Credit Card?
There is no universal answer.
The payoff period depends primarily on:
- Balance
- APR
- Monthly payment
- New purchases
- Fees
- Promotional rates
- Payment timing
For example, a $5,000 balance could potentially be paid off relatively quickly with a large fixed payment but may take substantially longer with a small payment.
The Basic Relationship
Higher payment → Faster payoff
Lower payment → Slower payoff
Higher APR → More interest
Lower APR → Less interest
Larger balance → More repayment required
Credit Card Payoff Example
Suppose you have:
Credit card balance = $5,000
APR = 24%
Monthly payment = $250
Using a simplified monthly-rate model:
Monthly rate = 24% ÷ 12 = 2%
The first month’s interest is approximately:
$5,000 × 2% = $100
After a $250 payment:
$5,000 + $100 − $250 = $4,850
The next month’s interest would be calculated on approximately $4,850.
The balance continues decreasing until it reaches zero.
A calculator repeats this process and estimates the total number of months and total interest.
$1,000 Credit Card Payoff Example
Consider a $1,000 credit card balance.
| APR | Monthly Payment | General Result |
|---|---|---|
| 15% | $100 | Relatively fast payoff |
| 20% | $100 | More interest |
| 25% | $100 | Higher interest |
| 30% | $100 | Highest interest |
The exact payoff period depends on the calculation method and any applicable fees.
The table demonstrates why the APR matters even when the balance and payment remain the same.
$5,000 Credit Card Payoff Example
Suppose:
Balance = $5,000
APR = 24%
Now compare different monthly payments.
| Monthly Payment | General Effect |
|---|---|
| $100 | Very slow payoff |
| $150 | Slow payoff |
| $200 | Faster |
| $250 | Faster |
| $300 | Significantly faster |
| $400 | Much faster |
The exact payoff period should be calculated using the calculator because interest continues to accrue while the balance remains outstanding.
$10,000 Credit Card Payoff Example
A larger balance makes the payment strategy even more important.
Suppose:
Balance = $10,000
APR = 24%
At a simplified 2% monthly rate, the initial monthly interest would be approximately:
$10,000 × 2% = $200
If your monthly payment were only $250, only about $50 would initially reduce the principal under this simplified example.
That demonstrates why a payment that seems large in absolute terms can still result in slow progress when the APR and balance are high.
How Paying More Can Save Interest
One of the simplest ways to reduce credit card interest is to pay more than the minimum when financially possible.
Consider:
Balance = $5,000
APR = 24%
Increasing your payment from:
$150 → $300
can significantly shorten the repayment period.
It can also reduce the number of months during which interest is charged.
Why This Works
Every dollar that reduces the balance can reduce future interest charges.
The effect can compound over multiple billing cycles.
Fixed Payment vs Minimum Payment
A fixed-payment strategy can make debt repayment easier to plan.
| Strategy | Advantage | Potential Disadvantage |
|---|---|---|
| Minimum payment | Lower immediate cash requirement | Can take much longer |
| Fixed higher payment | Predictable repayment | Requires more monthly cash |
| Large extra payment | Faster balance reduction | Less cash available for other needs |
| Full balance payment | Avoids interest on carried balance in many cases | Requires sufficient cash |
The best payment amount depends on your budget and financial situation.
Credit Card Payoff by Interest Rate
Suppose the balance and payment remain constant.
| APR | Interest Cost |
|---|---|
| 10% | Lower |
| 15% | Higher |
| 20% | Higher |
| 25% | Higher |
| 30% | Highest |
The higher the APR, the more expensive it generally is to carry a balance.
This is why reducing high-interest debt can be an important part of a debt repayment strategy.
Credit Card Payoff by Monthly Payment
Suppose the balance and APR remain constant.
| Monthly Payment | Payoff Speed |
|---|---|
| Minimum | Slowest |
| +$25 | Faster |
| +$50 | Faster |
| +$100 | Much faster |
| +$200 | Significantly faster |
| Large fixed payment | Fastest |
Even relatively small additional payments can reduce the number of months required to eliminate debt.
Debt Snowball Method
The debt snowball method focuses on paying off the smallest debt first while making required payments on other debts.
For example:
| Card | Balance |
|---|---|
| Card A | $700 |
| Card B | $2,000 |
| Card C | $5,000 |
Under a snowball strategy, you would generally focus extra money on Card A first.
After paying it off, the money previously used for Card A can be redirected toward Card B.
Why People Like the Snowball Method
The main advantage is psychological momentum.
Paying off a small balance can create a quick sense of progress.
However, it may not always minimize total interest.
Debt Avalanche Method
The debt avalanche method prioritizes the debt with the highest interest rate.
For example:
| Card | Balance | APR |
|---|---|---|
| Card A | $700 | 18% |
| Card B | $2,000 | 29% |
| Card C | $5,000 | 22% |
The avalanche method would generally prioritize Card B because it has the highest APR.
Why Avalanche Can Save Interest
Paying down the highest-rate balance first can reduce the amount of high-interest debt accumulating over time.
Snowball vs Avalanche
| Feature | Snowball | Avalanche |
|---|---|---|
| Priority | Smallest balance | Highest APR |
| Motivation | Strong | Moderate |
| Interest minimization | Not always optimal | Often better mathematically |
| Strategy | Psychological momentum | Mathematical efficiency |
Both methods can work.
The most important thing is maintaining a realistic repayment plan.
Multiple Credit Card Payoff Calculator
If you have multiple cards, calculating each balance separately may not provide the complete picture.
Suppose you have:
| Card | Balance | APR |
|---|---|---|
| Card A | $2,000 | 18% |
| Card B | $4,000 | 27% |
| Card C | $3,000 | 24% |
Total debt:
$9,000
A multiple-credit-card payoff strategy should consider:
- Balance
- APR
- Minimum payment
- Available monthly budget
- Payment allocation
A calculator can help compare different repayment strategies.
Balance Transfer and Credit Card Debt
A balance transfer may allow eligible debt to be moved to another credit card, sometimes with a promotional APR for a specified period.
However, balance transfers can involve:
- Transfer fees
- Promotional expiration dates
- Higher regular APR after the promotion
- Credit requirements
- Other account terms
A balance transfer can potentially reduce interest costs if used carefully, but it does not eliminate the debt.
Important Question
Before transferring a balance, calculate whether:
Interest savings − transfer fees
are actually positive.
A payoff calculator can help compare the scenarios.
Credit Card Payoff and New Purchases
A payoff calculation generally assumes that you stop adding new debt.
If you continue using the card while trying to repay it, the actual payoff time can be much longer.
For example:
Starting balance = $5,000
Monthly payment = $300
If you add another:
$200 of purchases each month
your balance may not decline as expected.
Therefore, when using a calculator, make sure you understand whether the calculation assumes no new purchases.
How to Use a Credit Cards Payoff Calculator
Using a Credit Cards Payoff Calculator is simple.
Step 1: Enter Your Current Balance
Enter the amount currently owed.
Example:
$5,000
Step 2: Enter Your APR
Enter the annual percentage rate from your credit card statement.
Example:
24%
Step 3: Enter Your Monthly Payment
Enter the amount you can realistically pay each month.
Example:
$300
Step 4: Enter Additional Information
If supported, enter:
- Minimum payment
- Additional monthly payment
- Fees
- Target payoff date
Step 5: Click Calculate
The calculator estimates your payoff period.
Step 6: Review the Results
Look at:
- Months remaining
- Total interest
- Total amount paid
- Estimated debt-free date
Step 7: Compare Different Payments
Try:
$200
$250
$300
$400
This can show how additional monthly payments may affect your debt-free timeline.
Benefits of Using a Credit Card Payoff Calculator
Know Your Debt-Free Date
You can estimate when your balance may reach zero.
Understand Interest Costs
The calculator can show how much money goes toward interest.
Compare Payment Strategies
You can test different monthly payments.
Set a Realistic Goal
A target payoff date becomes easier to plan when you know the required payment.
Reduce Financial Stress
Understanding the numbers can make debt feel more manageable.
Avoid Guesswork
Instead of estimating mentally, you can use a consistent mathematical calculation.
Build a Debt Repayment Plan
The calculator can be used as the first step in creating a broader debt-reduction strategy.
Common Credit Card Payoff Mistakes
Mistake 1: Paying Only the Minimum
Minimum payments can keep debt outstanding for a long time.
Mistake 2: Continuing to Add New Purchases
New purchases can offset your repayment progress.
Mistake 3: Ignoring APR
A high-interest card can become significantly more expensive over time.
Mistake 4: Using the Wrong APR
Always check the APR shown in your current card agreement or statement.
Mistake 5: Forgetting Fees
Late fees, annual fees, balance-transfer fees and other charges can affect the actual cost.
Mistake 6: Assuming the Calculator Is an Exact Statement
An online calculator is an estimate.
Your issuer may calculate interest differently.
Mistake 7: Setting an Unrealistic Payment
A repayment plan that you cannot maintain is unlikely to work.
Mistake 8: Closing a Card Without Understanding the Consequences
Closing a credit card can affect your available credit and potentially your credit utilization.
Consider the broader financial consequences before changing accounts.
Ways to Pay Off Credit Card Debt Faster
Pay More Than the Minimum
If your budget allows, increase your monthly payment.
Stop Adding New Debt
Avoid making unnecessary purchases on the card while paying it down.
Prioritize High-Interest Debt
Consider an avalanche strategy if minimizing interest is your primary goal.
Use Extra Income
You may choose to direct:
- Bonuses
- Tax refunds
- Freelance income
- Gifts
- Other available funds
toward debt repayment.
Reduce Unnecessary Expenses
Temporary reductions in discretionary spending can free up money for debt repayment.
Consider a Balance Transfer Carefully
A promotional balance transfer may help in some situations, but compare all fees and terms first.
Build an Emergency Fund
Without emergency savings, unexpected expenses can force you to rely on credit cards again.
Credit Card Payoff Strategy
A practical repayment strategy can look like this:
Step 1: List All Credit Cards
Record:
- Balance
- APR
- Minimum payment
- Due date
Step 2: Calculate Your Total Debt
Add all balances together.
Step 3: Choose a Strategy
Choose:
- Debt snowball
- Debt avalanche
- Fixed-payment approach
Step 4: Set a Monthly Debt Budget
Determine how much you can realistically dedicate to debt repayment.
Step 5: Stop Increasing the Balance
Avoid unnecessary new purchases.
Step 6: Track Progress
Update your balances regularly.
Step 7: Adjust When Your Financial Situation Changes
If your income increases, you may be able to increase debt payments.
If your expenses rise, adjust the plan realistically.
Real-Life Credit Card Payoff Examples
Example 1: $2,000 Balance
Suppose:
- Balance = $2,000
- APR = 20%
- Monthly payment = $150
The calculator can estimate the number of months required and total interest.
Now try:
Monthly payment = $250
The second scenario should generally result in:
- Faster payoff
- Lower total interest
- Earlier debt-free date
Example 2: $5,000 Balance
Suppose:
- Balance = $5,000
- APR = 25%
- Monthly payment = $200
Now compare it with:
Monthly payment = $350
The additional $150 per month can significantly change the payoff timeline.
Example 3: $10,000 Balance
Suppose:
- Balance = $10,000
- APR = 24%
- Monthly payment = $500
Compare this with:
Monthly payment = $750
The higher payment generally reduces both the repayment period and total interest.
Credit Card Payoff Comparison
Consider a hypothetical $5,000 balance.
| Monthly Payment | Expected Effect |
|---|---|
| $150 | Long repayment period |
| $200 | Moderate repayment |
| $250 | Faster |
| $300 | Faster still |
| $400 | Much faster |
| $500 | Very aggressive repayment |
The exact months and interest should be calculated using the user’s actual balance and APR.
How Much Should I Pay Toward Credit Card Debt?
There is no single payment amount that works for everyone.
Your payment should account for:
- Income
- Essential expenses
- Emergency savings
- Other debts
- Interest rates
- Financial goals
A good repayment plan should be aggressive enough to reduce debt but realistic enough to maintain.
If paying an extra $100 today means you will need to use the credit card again next week for essential expenses, the strategy may not be sustainable.
Should I Pay the Highest Interest Card First?
If your primary objective is to minimize interest mathematically, the debt avalanche method can be useful.
Pay the minimum required on all cards and direct additional money toward the card with the highest APR.
Once that card is paid off, move to the next-highest APR.
However, some people prefer the debt snowball method because paying off smaller balances can provide motivation.
Can a Credit Card Payoff Calculator Improve Your Credit Score?
A calculator itself does not improve your credit score.
However, paying down credit card balances can potentially improve your credit profile because credit utilization is one factor considered in many credit-scoring models.
Credit scoring systems vary, and paying debt does not guarantee a particular score increase.
The calculator’s main purpose is to help you understand your repayment timeline and interest cost.
Credit Card Payoff Calculator vs Loan Calculator
| Feature | Credit Card Payoff Calculator | Loan Calculator |
|---|---|---|
| Revolving debt | Yes | Usually no |
| Fixed term | Not necessarily | Usually |
| New purchases | Possible | Usually no |
| APR | Important | Important |
| Minimum payments | Common | Less common |
| Payoff date | Estimated | Usually known |
| Payment flexibility | High | Usually lower |
Credit card debt is revolving debt, while many traditional loans have fixed repayment schedules.
Frequently Asked Questions
What is a Credit Cards Payoff Calculator?
A Credit Cards Payoff Calculator estimates how long it may take to pay off credit card debt and how much interest you may pay based on your balance, APR and monthly payment.
How do I calculate how long it will take to pay off my credit card?
Enter your current balance, APR and monthly payment into a payoff calculator. The calculator can simulate monthly interest and payments until the balance reaches zero.
How much should I pay each month to pay off my credit card?
The required payment depends on your balance, APR and desired payoff period. A calculator can determine the approximate payment needed for a specific target date.
How long does it take to pay off a $5,000 credit card balance?
There is no single answer. It depends on the APR and monthly payment. Paying $500 per month will generally result in a much faster payoff than paying $150 per month.
How much interest will I pay on my credit card?
Your total interest depends on the balance, APR, payment amount, payment timing and how the card issuer calculates interest.
Does paying more than the minimum save money?
Generally, yes. Paying more toward principal can reduce the balance faster, which can reduce future interest charges.
What happens if I only make the minimum payment?
You may remain in debt for a long period, particularly if the APR is high and the balance is large. Your card statement generally provides information about minimum-payment repayment estimates.
What is the debt snowball method?
The debt snowball method focuses extra payments on your smallest balance while making required payments on other debts.
What is the debt avalanche method?
The debt avalanche method focuses extra payments on the debt with the highest interest rate.
Which is better: debt snowball or debt avalanche?
The avalanche method can reduce interest more efficiently in many cases, while the snowball method may provide stronger psychological motivation by producing quicker small-account victories.
Can I pay off credit card debt in one year?
Possibly. The required monthly payment depends on your total balance and APR. Use a payoff calculator to determine the payment needed to reach a 12-month payoff goal.
How do I pay off $10,000 in credit card debt?
Start by listing all balances and APRs, stop adding unnecessary new debt, determine your available monthly payment and choose a repayment strategy such as the avalanche or snowball method.
Can I use a Credit Cards Payoff Calculator for multiple cards?
Yes, if the calculator supports multiple balances. Otherwise, you can calculate each card separately and combine the results into a repayment plan.
Does a balance transfer eliminate credit card debt?
No. A balance transfer moves debt from one account to another. It may reduce interest during a promotional period, but the principal balance still needs to be repaid.
Are balance transfers free?
Not necessarily. Many balance-transfer offers can involve a transfer fee. Always review the specific card’s terms.
Does credit card interest compound?
Credit card interest calculations depend on the issuer’s agreement and calculation method. Interest may be calculated using a daily periodic rate and balance methodology rather than the simplified monthly model used by many online calculators.
Why is my calculator result different from my credit card statement?
The calculator may use a simplified monthly-interest model, while your credit card issuer may calculate interest using daily balances, daily periodic rates, payment timing, fees, promotional APRs or other account-specific rules.
Can I use this calculator for a 0% APR credit card?
Yes, if the calculator allows a 0% APR input. However, you should also consider when the promotional period ends and what APR applies afterward.
What if I keep using my credit card while paying it off?
New purchases increase the balance and can extend the payoff period. Most payoff calculations assume that you make no additional purchases.
Does paying off a credit card improve credit?
Paying down revolving balances can potentially improve credit utilization, but credit-score changes depend on your complete credit profile and the scoring model used.
Should I use savings to pay off credit card debt?
It depends on your financial situation. High-interest debt can be expensive, but maintaining an emergency fund can also be important. Consider both factors rather than automatically using all available savings.
Is a Credit Card Payoff Calculator accurate?
It can accurately calculate results according to its assumptions, but the result may differ from your actual statement because credit card issuers can use different interest calculations and account terms.
Can I calculate a debt-free date?
Yes. If you know your balance, APR and planned monthly payment, a payoff calculator can estimate the month in which your balance may reach zero.
What is the best way to pay off credit card debt?
The best approach depends on your financial situation. Common strategies include paying more than the minimum, stopping new purchases, using the debt avalanche or snowball method and maintaining a sustainable monthly budget.
Important Credit Card Payoff Calculator Disclaimer
The CalculatorsGlobal.com Credit Cards Payoff Calculator provides estimates for educational and planning purposes.
Actual credit card interest and repayment periods can vary based on the issuer’s calculation method, daily balances, APR changes, fees, promotional rates, payment timing, new purchases and other account-specific terms.
Calculator results should not be considered a statement from your credit card issuer or financial advice.
Always review your credit card agreement and billing statement for the exact applicable APR, minimum payment, fees and repayment terms.
Conclusion
A Credit Cards Payoff Calculator can turn a confusing credit card balance into a clear repayment plan.
Instead of asking, “How long will it take to pay off my credit card?” you can enter your balance, APR and monthly payment and estimate your potential debt-free date, total interest and total repayment amount.
The most important variables are:
- Current balance
- APR
- Monthly payment
- New purchases
- Fees
- Payment timing
In general, paying more than the minimum can help reduce the balance faster and potentially reduce total interest.
If you have multiple credit cards, consider comparing the debt snowball and debt avalanche approaches. The snowball method focuses on the smallest balance, while the avalanche method focuses on the highest interest rate.
Most importantly, create a payment plan that is realistic for your budget. A sustainable repayment strategy is more useful than a payment amount that looks good on paper but cannot be maintained.
Use the CalculatorsGlobal.com Credit Cards Payoff Calculator to experiment with different monthly payments and see how small changes could affect your journey toward becoming debt-free.