An Annuity Payout Calculator estimates periodic income from an annuity using factors such as the initial amount, interest rate, payment frequency and payout period. For a fixed-period ordinary annuity, a common payment formula is PMT = PV × r ÷ [1 − (1 + r)^−n], where PV is the present value, r is the periodic interest rate and n is the number of payments. Retirement Calculator — Social Security Calculator — Compound Interest Calculator — Interest Rate Calculator — Investment Calculator — Inflation Calculator — 401(k) Calculator — Present Value Calculator —Future Value Calculator — Percentage Calculator
Annuity Payout Calculator: Calculate Monthly, Annual & Lifetime Annuity Payments
An Annuity Payout Calculator helps you estimate how much income you may receive from an annuity based on factors such as your initial investment, interest rate, payout period and payment frequency.
Annuities are commonly used for retirement planning because they can convert a lump sum or a series of contributions into a stream of periodic income. Depending on the contract, payments may begin immediately or at a later date and may continue for a fixed period or for the lifetime of one or more people.
For example, suppose you have $200,000 available for retirement and want to understand how much income a fixed-period annuity could provide each month. An annuity payout calculator can estimate the payment using the amount invested, assumed interest rate and number of payments.
However, there is an important distinction between a mathematical annuity payout calculation and an actual quote from an insurance company.
A simple financial calculator can estimate payments for a fixed-period annuity using an annuity formula. A real-life lifetime annuity purchased from an insurer can involve additional factors such as age, life expectancy, interest rates, contract guarantees, fees and the selected payout option. FINRA notes that insurers consider factors including age, life expectancy, prevailing interest rates and their own pricing when determining payments.
This guide explains how an annuity payout calculator works, the formulas behind annuity payments, fixed-period versus lifetime annuities, immediate and deferred annuities, payout examples, monthly income calculations, annuity comparisons and the important factors to consider before purchasing an annuity.
What Is an Annuity Payout Calculator?
An Annuity Payout Calculator is an online financial calculator that estimates the periodic income generated by an annuity.
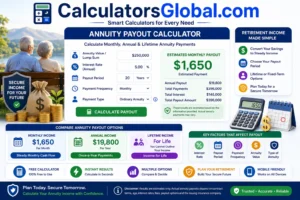
Depending on the calculator, you may enter:
- Initial investment
- Current annuity value
- Interest rate
- Payout period
- Number of payments per year
- Payment start date
- Payment frequency
- Desired payout duration
The calculator can then estimate:
- Monthly payment
- Quarterly payment
- Annual payment
- Total payments
- Total interest
- Remaining balance, depending on the calculation
An annuity is generally a contract with an insurance company under which you make a lump-sum payment or a series of payments and receive periodic income payments either immediately or at a future date.
Why Use an Annuity Payout Calculator?
It can help you understand how much income a particular amount might generate.
For example, you could compare:
$100,000 → 10-year payout
with:
$100,000 → 20-year payout
or compare different assumed interest rates.
This makes it easier to understand the relationship between:
Investment Amount → Interest → Payout Period → Periodic Income
What Is an Annuity?
An annuity is a financial contract designed to provide periodic payments, often for retirement or other long-term financial goals.
You may make:
- One lump-sum payment
- Multiple payments
- Regular contributions
The insurer may then provide:
- Monthly payments
- Quarterly payments
- Semiannual payments
- Annual payments
- Lifetime income
- Fixed-period income
The exact options depend on the annuity contract.
Investor.gov explains that annuities can provide periodic income for a specific period, for life, or for the lives of a spouse or partner, depending on the contract.
Why Do People Buy Annuities?
Annuities are commonly considered for:
- Retirement income
- Long-term income planning
- Lifetime income needs
- Reducing the risk of outliving certain retirement assets
- Creating predictable periodic payments
However, annuities can also involve fees, restrictions and contract-specific risks, so the payout should not be the only factor considered.
How Do Annuities Work?
An annuity generally has two broad stages.
Accumulation Phase
During the accumulation phase, money is contributed to the annuity and may grow according to the contract.
This stage is particularly relevant to deferred annuities.
Payout Phase
During the payout phase, the contract begins distributing income according to the selected payout option.
For example:
$250,000 annuity value
could potentially be converted into:
Monthly retirement income
The actual payment depends on the contract terms.
Investor.gov describes the payout phase as the period when annuity income payments begin.
Annuity Accumulation Phase
The accumulation phase is the period during which money is being contributed to or accumulated within the annuity.
Depending on the product, the value may be affected by:
- Contributions
- Interest
- Investment performance
- Contract fees
- Withdrawals
Fixed, indexed and variable annuities can have very different accumulation characteristics.
Example
Suppose you contribute:
$100,000
and the contract grows over several years.
At the end of the accumulation period, the contract might have a value of:
$140,000
You could then potentially use that value to generate retirement income, depending on the contract.
The actual value will depend on the specific annuity.
Annuity Payout Phase
The payout phase begins when the annuity starts making income payments.
Payments may be structured as:
- Fixed monthly payments
- Fixed annual payments
- Lifetime payments
- Joint lifetime payments
- Fixed-period payments
- Other contract-specific options
The payout amount can vary significantly depending on which option you select.
For example, choosing a lifetime payment with no refund feature can produce a different payout from a joint-life option or a period-certain option.
Immediate vs Deferred Annuity
One of the most important distinctions is between immediate annuities and deferred annuities.
Immediate Annuity
An immediate annuity generally has no accumulation phase. Payments typically begin shortly after purchase.
For example:
$300,000 lump sum → Immediate annuity → Monthly income
The exact payment depends on the contract.
Deferred Annuity
A deferred annuity has an accumulation period before income payments begin.
For example:
Age 55 → Purchase annuity
Age 65 → Begin income payments
Investor.gov describes deferred annuities as contracts where payments or contributions accumulate before the income phase begins.
Immediate vs Deferred Annuity
| Feature | Immediate Annuity | Deferred Annuity |
|---|---|---|
| Accumulation period | Generally none | Yes |
| Income begins | Shortly after purchase | Later |
| Common purpose | Immediate retirement income | Future retirement income |
| Growth period | Limited/none before payout | Yes |
| Suitable for | Immediate income needs | Future income planning |
Fixed vs Variable Annuity
Annuities can also differ based on how their value and payments are determined.
Fixed Annuity
A fixed annuity can provide a specified or guaranteed minimum rate during the applicable period, subject to the contract terms.
Variable Annuity
A variable annuity generally allows investment in selected investment options, and the value can change based on investment performance and expenses.
Fixed Indexed Annuity
A fixed indexed annuity can credit interest based partly on the performance of a specified index, subject to contract terms and limits.
Comparison
| Type | Main Characteristic |
|---|---|
| Fixed | Contractual interest/benefit structure |
| Variable | Value linked to selected investment options |
| Fixed Indexed | Interest crediting linked partly to an index |
| Immediate | Income starts shortly after purchase |
| Deferred | Income starts later |
The exact guarantees, fees and risks depend on the individual contract.
Annuity Payout Formula
For a standard fixed-period ordinary annuity, the periodic payment can be calculated using:
PMT = PV × r ÷ [1 − (1 + r)^−n]
Where:
- PMT = periodic payment
- PV = present value or amount being annuitized
- r = interest rate per payment period
- n = total number of payments
The formula assumes payments occur at the end of each payment period.
Example
Suppose:
PV = $100,000
Annual interest rate = 6%
Monthly payments
Payout period = 10 years
Monthly rate:
6% ÷ 12 = 0.5%
Number of payments:
10 × 12 = 120
The monthly payment can then be estimated using the annuity formula.
This is a mathematical estimate for a fixed-term payment stream. It is not the same thing as an insurer’s quote for a lifetime annuity.
How to Calculate Annuity Payments
To calculate a fixed-period annuity payment manually:
Step 1: Determine the Present Value
This is the amount being converted into payments.
Example:
$200,000
Step 2: Convert the Interest Rate
If the annual rate is 6% and payments are monthly:
Monthly rate = 6% ÷ 12
Monthly rate = 0.5%
As a decimal:
r = 0.005
Step 3: Calculate Number of Payments
For a 15-year monthly payout:
15 × 12 = 180 payments
Step 4: Apply the Formula
Use:
PMT = PV × r ÷ [1 − (1 + r)^−n]
Step 5: Review the Result
The resulting PMT represents the estimated periodic payment under the assumptions used.
Monthly Annuity Payment Calculator
A Monthly Annuity Payment Calculator converts an annuity value into estimated monthly payments.
Monthly payments are common because they resemble a regular retirement paycheck.
Suppose:
Annuity value = $250,000
Annual interest assumption = 5%
Payout period = 20 years
Payments = monthly
The calculator converts the annual rate into a monthly rate and the years into monthly payment periods.
Why Monthly Payments Are Useful
Monthly income can help with:
- Rent or mortgage
- Groceries
- Utilities
- Insurance
- Healthcare
- Transportation
- Other retirement expenses
However, monthly payment frequency may produce a different result from annual payments because interest is applied over different payment periods.
Annual Annuity Payment Calculator
An annual annuity calculator estimates how much you could receive once per year.
For example:
Annuity value = $200,000
Rate = 5%
Payout period = 15 years
The calculator estimates the annual payment using the appropriate annuity formula.
Annual payments may be useful when planning:
- Annual expenses
- Property taxes
- Insurance
- Large retirement expenses
- Long-term cash flow
Fixed-Term Annuity Payout Calculator
A fixed-term annuity provides payments for a predetermined period.
For example:
10 years
15 years
20 years
The number of payments is known in advance.
Example
Suppose:
Investment = $150,000
Payout = 15 years
Frequency = Monthly
Number of payments:
15 × 12 = 180
The calculator can estimate the monthly payment based on the assumed rate.
Important Difference
A fixed-term annuity is different from a lifetime annuity.
With a fixed-term annuity, the payment period is specified.
With a lifetime annuity, the payment period depends on how long the annuitant lives and the contract terms.
Lifetime Annuity Payout Calculator
A Lifetime Annuity Calculator estimates potential income for life.
However, lifetime annuity payments cannot be accurately determined using only a standard time-value-of-money formula.
The insurer may consider:
- Age
- Life expectancy
- Interest rates
- Payment frequency
- Single-life vs joint-life
- Guaranteed period
- Death benefit
- Refund option
- Contract expenses
- Insurance company pricing
FINRA notes that insurers consider age, life expectancy, prevailing interest rates and other factors when determining annuity payments.
Why Lifetime Payments Can Be Different
Imagine two people each have:
$300,000
One person is age 60.
Another person is age 75.
The expected duration of payments is different, so an insurer may offer different monthly payout amounts.
Therefore, a generic calculator should clearly identify whether it is estimating a fixed-period annuity or attempting to estimate a lifetime annuity.
Annuity Payout From a Lump Sum
Many people want to answer a simple retirement question:
“If I have $500,000, how much monthly income could it generate?”
The answer depends on the payout method.
For a fixed-period mathematical annuity, you can use:
PMT = PV × r ÷ [1 − (1 + r)^−n]
For a lifetime insurance annuity, the actual quote depends on the insurance contract.
Example
Suppose:
Lump Sum = $500,000
You want income for:
20 years
At an assumed:
5% annual rate
The calculator can estimate a fixed monthly payment.
If you instead purchase a lifetime annuity, the insurer’s quoted payment may be substantially different.
Annuity Payout With Interest
Interest can affect the amount of income generated from a fixed-term annuity.
Consider two hypothetical scenarios:
| Investment | Rate | Term | Payment Frequency |
|---|---|---|---|
| $200,000 | 3% | 20 years | Monthly |
| $200,000 | 6% | 20 years | Monthly |
The higher assumed rate generally produces a higher periodic payment if all other assumptions remain the same.
However, a higher assumed rate should not be interpreted as a guaranteed investment return.
Annuity Payout Example
Let’s use a simplified fixed-term example.
Initial amount: $100,000
Interest rate: 6%
Payout period: 10 years
Payment frequency: Monthly
Number of payments:
10 × 12 = 120
Monthly interest rate:
6% ÷ 12 = 0.5%
Using the ordinary-annuity payment formula produces an estimated monthly payment of approximately:
$1,110
Total payments over 10 years would be approximately:
$133,200
The difference between total payments and the original $100,000 represents the effect of the assumed interest over the payout period.
This example is a mathematical illustration and does not represent an insurance company’s actual annuity quote.
Annuity Payout at Different Interest Rates
Suppose the same:
$100,000
is paid out over:
10 years
with monthly payments.
The assumed interest rate can change the estimated payment.
| Assumed Rate | General Effect on Payment |
|---|---|
| 2% | Lower |
| 3% | Higher than 2% |
| 4% | Higher than 3% |
| 5% | Higher than 4% |
| 6% | Higher than 5% |
| 7% | Higher than 6% |
This comparison assumes the same starting amount, payment frequency and fixed payout period.
Annuity Payout by Investment Amount
A larger initial amount generally produces a larger payment when the rate and payout period are unchanged.
For example:
| Initial Amount | General Payment Potential |
|---|---|
| $50,000 | Lower |
| $100,000 | Higher |
| $200,000 | Higher |
| $300,000 | Higher |
| $500,000 | Higher |
| $1,000,000 | Highest |
This is a general mathematical relationship, not a guarantee of any particular insurance payout.
Annuity Payout by Payment Period
The payout period also affects the payment.
Suppose you have the same amount and interest rate.
A shorter payout period generally requires a larger periodic payment.
A longer payout period generally produces a smaller periodic payment.
| Payout Period | Typical Payment Relationship |
|---|---|
| 5 years | Higher periodic payment |
| 10 years | Lower |
| 15 years | Lower |
| 20 years | Lower |
| 30 years | Lower |
This assumes a fixed-period annuity with otherwise identical assumptions.
Annuity Due vs Ordinary Annuity
Another important concept is the timing of payments.
Ordinary Annuity
Payments occur at the end of each period.
Examples:
- End of each month
- End of each quarter
- End of each year
Annuity Due
Payments occur at the beginning of each period.
Because payments occur earlier, an annuity due generally produces a higher payment than an ordinary annuity when the present value, rate and number of periods are otherwise identical.
Comparison
| Feature | Ordinary Annuity | Annuity Due |
|---|---|---|
| Payment timing | End of period | Beginning of period |
| First payment | After one period | Immediately/at start |
| Interest accumulation | Longer before first payment | Shorter |
| Payment amount | Lower | Generally higher |
A calculator should clearly state which payment timing it assumes.
Annuity Payout vs Lump Sum
Choosing between an annuity and keeping a lump sum is an important financial decision.
Annuity
Potential advantages:
- Predictable income
- Retirement cash flow
- Potential lifetime income
- Reduced need to manage withdrawals
Potential disadvantages:
- Reduced liquidity
- Contract restrictions
- Fees
- Possible surrender charges
- Inflation risk
- Insurer credit risk
- Less flexibility
Investor.gov notes that annuities can involve surrender charges, taxes, fees and other contract-specific considerations.
Lump Sum
Potential advantages:
- More flexibility
- Easier access to money
- Ability to invest elsewhere
- Greater control over withdrawals
Potential disadvantages:
- Investment risk
- Longevity risk
- Risk of overspending
- No automatic lifetime income unless separately arranged
There is no universally best option.
Annuity Payout and Inflation
Inflation is an important consideration when evaluating retirement income.
Suppose an annuity pays:
$2,000 per month
If the payment stays fixed while prices increase, the purchasing power of that $2,000 may decline over time.
FINRA specifically warns that inflation can erode the purchasing power of most annuity payments over time.
Inflation Example
Suppose your monthly income is:
$3,000
If prices rise significantly over 20 years, $3,000 in the future may purchase considerably less than $3,000 today.
Some annuity contracts offer inflation-adjusted or increasing payment features, but these features can affect the initial payout and contract cost.
Always check the actual contract.
Annuity Fees and Charges
Fees can affect the value of an annuity and the overall return.
Possible costs can include:
- Administrative fees
- Investment expenses
- Rider fees
- Surrender charges
- Sales-related charges
- Contract fees
Investor.gov notes that fees can reduce the value of an annuity and that some costs may be explicit while others may be less visible.
Why Fees Matter
Suppose two annuities appear to offer similar returns.
If one has substantially higher expenses, the difference can reduce the value available for retirement income.
Always review the actual contract and disclosure documents.
Annuity Death Benefits
Some annuities provide death benefits.
Depending on the contract, a beneficiary may receive some amount if the annuitant dies.
Possible structures include:
- Return of premium
- Remaining contract value
- Guaranteed payment period
- Specific death benefit
- Joint-life continuation
The trade-off is that additional guarantees or beneficiary protections can affect the payout amount.
Investor.gov recommends understanding how the death benefit is calculated and what happens to the contract after death.
How to Use an Annuity Payout Calculator
Using the calculator is generally simple.
Step 1: Enter the Annuity Value
Enter the amount available for payout.
Example:
$250,000
Step 2: Enter the Interest Rate
Enter the assumed annual rate.
Example:
5%
Step 3: Select Payment Frequency
Choose:
- Monthly
- Quarterly
- Semiannual
- Annual
Step 4: Enter Payout Period
For a fixed-term calculation, enter the number of years.
Example:
20 years
Step 5: Choose Payment Timing
If supported, select:
- Ordinary annuity
- Annuity due
Step 6: Click Calculate
The calculator provides the estimated payment.
Step 7: Compare Scenarios
Try different:
- Interest rates
- Investment amounts
- Payout periods
- Payment frequencies
This can help you understand how each variable affects income.
Common Annuity Calculation Mistakes
Mistake 1: Assuming an Annuity Calculator Gives an Insurance Quote
A mathematical estimate is not the same as an insurer’s actual quote.
Mistake 2: Ignoring Payment Frequency
Monthly and annual payment calculations are not interchangeable.
Mistake 3: Forgetting Payment Timing
Annuity due and ordinary annuity calculations are different.
Mistake 4: Ignoring Fees
Fees can reduce the amount available for investment or income.
Mistake 5: Ignoring Inflation
A fixed payment may lose purchasing power over time.
Mistake 6: Ignoring Surrender Charges
Some annuities impose surrender charges for certain withdrawals during the surrender period.
Mistake 7: Assuming Lifetime Income Is the Same as Fixed-Term Income
Lifetime annuities involve longevity and insurance calculations that differ from ordinary fixed-period formulas.
Mistake 8: Comparing Only the Monthly Payment
A larger monthly payment may come with fewer guarantees, less liquidity or different beneficiary provisions.
Benefits of an Annuity Payout Calculator
Fast Calculations
Calculate estimated payments within seconds.
Easy Comparison
Compare different payout periods and rates.
Retirement Planning
Estimate how much income a retirement asset might generate.
Understand Cash Flow
See how a lump sum could translate into periodic income.
Compare Payment Frequencies
Compare monthly and annual income scenarios.
Explore Different Investment Amounts
Test $100,000, $250,000, $500,000 and other amounts.
Improve Financial Understanding
The calculator helps explain how present value, interest and payment periods interact.
Real-Life Annuity Examples
Example 1: $100,000 Annuity
Suppose:
- Investment = $100,000
- Rate = 5%
- Term = 10 years
- Payments = Monthly
The calculator estimates a fixed monthly payment based on these assumptions.
Example 2: $250,000 Annuity
Suppose:
- Investment = $250,000
- Rate = 5%
- Term = 20 years
- Payments = Monthly
A longer payout period generally means a lower monthly payment than a shorter period, assuming the other variables remain unchanged.
Example 3: $500,000 Retirement Annuity
Suppose:
- Investment = $500,000
- Rate assumption = 5%
- Term = 20 years
- Payments = Monthly
A calculator can estimate the fixed-period income.
However, if you are considering a lifetime insurance annuity, you should compare the estimate with an actual insurer quote because lifetime payouts depend on additional factors.
Annuity Payout Comparison Table
| Variable | Increase in Variable | General Effect |
|---|---|---|
| Initial investment | Higher | Higher potential payment |
| Interest rate | Higher | Higher payment for fixed-term calculation |
| Payout period | Longer | Lower periodic payment |
| Payout period | Shorter | Higher periodic payment |
| Payment frequency | More frequent | Changes periodic amount |
| Fees | Higher | Lower net value/payment |
| Inflation | Higher | Lower purchasing power of fixed payments |
Fixed-Term vs Lifetime Annuity
| Feature | Fixed-Term Annuity | Lifetime Annuity |
|---|---|---|
| Payment duration | Predetermined | Based on lifetime |
| Number of payments | Known/estimated | Unknown |
| Longevity risk | Remains with investor | Can be transferred to insurer |
| Mathematical calculation | Relatively straightforward | More complex |
| Insurance pricing | Limited/contract dependent | Major factor |
| Payment certainty | Depends on contract | Depends on guarantee terms |
Immediate Annuity vs Deferred Annuity
| Feature | Immediate | Deferred |
|---|---|---|
| Income start | Soon after purchase | Later |
| Accumulation phase | Generally none | Yes |
| Common use | Immediate retirement income | Future retirement income |
| Investment horizon | Shorter before payout | Longer before payout |
Frequently Asked Questions
What is an Annuity Payout Calculator?
An Annuity Payout Calculator estimates periodic income from an annuity using variables such as investment amount, interest rate, payout period and payment frequency.
How is an annuity payout calculated?
For a fixed-term ordinary annuity, a common formula is:
PMT = PV × r ÷ [1 − (1 + r)^−n]
PV represents the present value, r the periodic interest rate and n the number of payments.
How much does a $100,000 annuity pay per month?
There is no single answer. The monthly payment depends on the interest assumption, payout period, payment timing and whether it is a fixed-period or lifetime annuity.
How much does a $500,000 annuity pay per month?
The answer depends on the annuity type, payout period, interest assumptions, age, payment option and contract terms. A fixed-period calculator can provide a mathematical estimate, while a lifetime annuity requires an insurer quote.
What is an immediate annuity?
An immediate annuity generally begins making payments shortly after purchase rather than having a long accumulation period.
What is a deferred annuity?
A deferred annuity has an accumulation period before income payments begin.
What is the difference between an annuity and a retirement account?
An annuity is an insurance contract that can provide periodic income, while a retirement account is generally an investment or savings account with its own tax and withdrawal rules.
Can an annuity provide lifetime income?
Yes. Certain annuity contracts can provide income for the lifetime of an individual or joint lives, depending on the selected contract option.
Does an annuity guarantee income?
Some annuity contracts offer contractual guarantees, but guarantees depend on the specific contract and the insurer’s ability to meet its obligations.
Does an annuity payout increase with inflation?
Not necessarily. Some payments are fixed. Certain contracts may offer increasing or inflation-related features, but these can have different costs and payout structures.
What is an annuity due?
An annuity due makes payments at the beginning of each period rather than the end.
What is an ordinary annuity?
An ordinary annuity makes payments at the end of each period.
Does a higher interest rate increase annuity payments?
For a fixed-period mathematical annuity, a higher assumed rate generally increases the periodic payment when all other variables remain unchanged.
Does a longer payout period increase the monthly payment?
Generally no. With the same starting amount and interest rate, spreading payments over a longer period generally reduces the periodic payment.
Are annuity calculator results guaranteed?
No. Calculator results are estimates based on the assumptions entered. They should not be treated as an insurance company’s guaranteed quote.
Are annuity payments taxable?
Tax treatment depends on the type of annuity, how it was purchased, the account structure and applicable tax rules. Consult current tax guidance for your specific situation.
What are annuity surrender charges?
A surrender charge is a fee that may apply when money is withdrawn during a specified surrender period.
Can I withdraw money from an annuity?
Withdrawal rules vary by contract. Some annuities permit withdrawals but may impose surrender charges, taxes or other consequences.
What happens to my annuity when I die?
It depends on the contract. Some annuities have death benefits or guaranteed payment periods, while others may stop payments at death.
Is an annuity better than taking a lump sum?
There is no universal answer. An annuity can provide predictable income, while a lump sum provides greater flexibility and control. The right choice depends on retirement goals, liquidity needs, risk tolerance, taxes and contract terms.
What factors determine a lifetime annuity payout?
Factors can include age, life expectancy, interest rates, payout option, single-life or joint-life selection, guarantees, fees and the insurer’s pricing.
Is an annuity calculator the same as an annuity quote?
No. A calculator provides an estimate based on assumptions. An insurer’s quote is based on its actual contract terms and pricing.
Can I calculate an annuity payout from a lump sum?
Yes. For a fixed-period annuity, the lump sum can be used as the present value in the annuity payment formula.
Important Annuity Calculator Disclaimer
The CalculatorsGlobal.com Annuity Payout Calculator is intended for general educational and estimation purposes.
Calculator results are based on the information and assumptions entered and may differ from actual annuity payments offered by an insurance company.
Actual annuity payouts can depend on contract terms, interest rates, age, life expectancy, fees, payment options, guarantees, death benefits and the financial strength of the issuing insurer.
Before purchasing an annuity or making an important retirement decision, review the actual contract and consider obtaining professional financial and tax advice where appropriate.
Conclusion
An Annuity Payout Calculator can make retirement-income planning easier by showing how a lump sum could potentially be converted into periodic payments.
For a fixed-period annuity, the basic calculation uses the present value, periodic interest rate and number of payments:
PMT = PV × r ÷ [1 − (1 + r)^−n]
The result can help you estimate monthly, quarterly or annual income.
However, a mathematical annuity calculation should not be confused with an actual lifetime annuity quote. Real insurance annuity payouts can depend on age, life expectancy, interest rates, payout options, guarantees, fees and the insurer’s pricing.
Before evaluating an annuity, compare more than just the monthly payment. Look at:
- Guaranteed income
- Payout duration
- Inflation protection
- Fees
- Surrender charges
- Liquidity
- Death benefits
- Beneficiary provisions
- Insurer financial strength
- Tax treatment
- Contract restrictions
Investor.gov also recommends understanding the annuity’s fees, benefits, risks and the financial strength of the insurance company before purchasing an annuity.
Use the CalculatorsGlobal.com Annuity Payout Calculator to estimate your potential periodic income and compare different investment amounts, interest rates and payout periods.