A Social Security Calculator estimates your potential Social Security retirement benefit using information such as your earnings history, birth date, expected retirement date and claiming age. The most accurate personal estimate comes from your official Social Security earnings record and SSA’s personalized tools. Retirement Calculator — 401(k) Calculator — Investment Calculator — Compound Interest Calculator — Inflation Calculator — Percentage Calculator — Age Calculator — Income Tax Calculator — Salary Calculator — Interest Rate Calculator
Social Security Calculator: Estimate Your Retirement Benefits
Social Security Calculator to estimate retirement benefits based on earnings, claiming age and retirement year. Learn how Social Security benefits are calculated.
Planning for retirement can be difficult when you do not know how much income you may receive from Social Security. A Social Security Calculator can help you estimate your potential monthly retirement benefit and understand how factors such as your earnings history and claiming age can affect your future payments.
Social Security retirement benefits are not based on one simple salary percentage. The Social Security Administration considers your covered earnings history, the number of years you worked, your age when you claim benefits, and other factors.
For many workers, the difference between claiming at age 62, claiming at full retirement age, and delaying benefits until age 70 can be substantial.
The official Social Security Administration says retirement benefits are based on earnings and the age at which benefits begin. SSA also provides personalized estimates through a person’s my Social Security account.
A Social Security Calculator can therefore be useful for:
- Retirement planning
- Estimating monthly Social Security income
- Comparing different claiming ages
- Understanding early retirement reductions
- Understanding delayed retirement credits
- Estimating the effect of future earnings
- Comparing retirement scenarios
- Planning savings and investment needs
What Is a Social Security Calculator?
A Social Security Calculator is an online retirement planning tool that estimates how much you may receive in Social Security benefits.
The calculator may use information such as:
- Date of birth
- Current age
- Annual earnings
- Previous earnings
- Expected future earnings
- Retirement age
- Benefit claiming age
- Expected retirement year
Depending on the calculator, the result may include an estimated:
- Monthly retirement benefit
- Annual retirement benefit
- Benefit at age 62
- Benefit at full retirement age
- Benefit at age 70
- Retirement income comparison
The official SSA calculator can produce estimates based on earnings information entered by the user, while a person’s my Social Security account can provide personalized estimates using their earnings record.
What Does a Social Security Calculator Tell You?
A useful calculator can help answer questions such as:
- How much Social Security could I receive?
- When can I start receiving retirement benefits?
- What happens if I claim at 62?
- What happens if I wait until full retirement age?
- What happens if I wait until 70?
- How much could additional earnings affect my benefit?
- How much retirement income might Social Security provide?
It is important to remember that an online calculator provides an estimate, not a guaranteed future payment.
How Does a Social Security Calculator Work?
A Social Security Calculator generally starts with your age and earnings information.
Step 1: Enter Your Date of Birth
Your birth year helps determine your Full Retirement Age (FRA) and the potential adjustment for claiming benefits early or delaying benefits.
For people born in 1960 or later, the full retirement age is 67.
Step 2: Enter Your Earnings
The calculator may ask for your current annual earnings and previous earnings.
SSA calculates retirement benefits using covered earnings, and higher earnings generally result in a higher benefit.
Step 3: Enter Your Expected Retirement Age
You can compare different claiming ages.
For example:
- Age 62
- Age 65
- Age 67
- Age 70
Step 4: Calculate Your Estimate
The calculator processes your information and provides an estimated benefit.
Step 5: Compare Different Scenarios
A good retirement calculator should allow you to compare how claiming at different ages changes your estimated monthly benefit.
Why Use a Social Security Calculator?
Retirement planning becomes easier when you have an idea of your potential guaranteed income sources.
Estimate Retirement Income
Your estimated Social Security benefit can become one part of your retirement-income plan.
Compare Claiming Ages
You can compare the potential benefit at age 62, full retirement age and later ages.
Plan Retirement Savings
If your expected Social Security income is lower than your desired retirement income, you may need additional savings or investment income.
Evaluate Working Longer
Additional years of earnings may affect your eventual benefit, especially if newer earnings replace lower-earning years in your benefit calculation. SSA notes that benefits are based on the highest 35 years of earnings.
Make Retirement Decisions
A calculator can help you understand the financial consequences of different claiming strategies.
How Social Security Benefits Are Calculated
Social Security retirement benefits involve a more complex calculation than simply taking a percentage of your final salary.
SSA generally bases retirement benefits on your earnings history and the age at which you begin receiving benefits.
One important concept is the Average Indexed Monthly Earnings (AIME).
Another is the Primary Insurance Amount (PIA).
The PIA is then adjusted depending on when you claim benefits.
Simplified Calculation Process
A simplified overview looks like this:
Covered Earnings → Indexed Earnings → Highest 35 Years → AIME → PIA → Claiming-Age Adjustment → Estimated Benefit
This is a conceptual explanation rather than the complete official SSA calculation.
Social Security Benefit Formula
The official Social Security benefit calculation uses a progressive formula applied to Average Indexed Monthly Earnings.
The calculation involves bend points, which are adjusted periodically.
Because these values can change over time, a consumer-facing calculator should use current SSA figures when performing an official-style estimate.
For a personalized estimate, the SSA’s official tools are preferable because they can use your actual earnings record.
Average Indexed Monthly Earnings
Average Indexed Monthly Earnings, commonly called AIME, is an important part of the Social Security retirement benefit calculation.
In simplified terms, SSA adjusts historical covered earnings for wage growth and then uses the highest relevant earnings years to calculate an average monthly amount.
SSA states that retirement benefits are based on a worker’s highest 35 years of earnings. If a person has fewer than 35 years of earnings, years without earnings can affect the benefit calculation.
Why 35 Years Matter
Suppose a worker has:
35 years of covered earnings
Those years can provide a complete earnings history for the basic calculation.
Now consider another worker with:
25 years of covered earnings
The remaining years may be treated as zero-earning years in the benefit calculation.
That can reduce the average.
This is one reason working longer can potentially increase Social Security benefits.
Primary Insurance Amount
The Primary Insurance Amount (PIA) is the benefit amount associated with claiming at full retirement age.
The actual benefit you receive can differ from your PIA depending on when you begin claiming.
Claim Before Full Retirement Age
Your monthly benefit is reduced.
Claim at Full Retirement Age
You generally receive your full retirement benefit.
Claim After Full Retirement Age
Your benefit can increase through delayed retirement credits until age 70.
SSA confirms that delayed retirement credits stop accumulating after age 70.
Full Retirement Age
Full Retirement Age, or FRA, is the age at which a person becomes eligible for their full Social Security retirement benefit.
Your FRA depends on your year of birth.
For people born in 1960 or later:
Full Retirement Age = 67
For earlier birth years, the FRA can be different.
Why Full Retirement Age Matters
FRA is important because claiming before FRA can reduce your monthly benefit.
Waiting until FRA generally avoids the early-claiming reduction.
Waiting beyond FRA can increase the monthly benefit through delayed retirement credits.
Claiming Social Security at Age 62
Age 62 is generally the earliest age at which a person can begin receiving Social Security retirement benefits.
However, claiming before full retirement age results in a reduced monthly benefit.
For someone whose FRA is 67, claiming at 62 can result in a reduction of up to 30% compared with the full-retirement-age benefit.
Example
Suppose a worker’s full retirement benefit is:
$2,500 per month
If the worker claims significantly earlier than FRA, the monthly benefit can be reduced.
The exact reduction depends on the person’s birth year and claiming month.
Therefore, a Social Security Calculator should use the individual’s actual date of birth and intended claiming date rather than applying a generic percentage.
Claiming Social Security at Full Retirement Age
Claiming at FRA generally provides the worker’s full retirement benefit amount.
For someone born in 1960 or later:
FRA = 67
If a person’s estimated FRA benefit is:
$2,500 per month
then claiming at FRA would generally provide the unreduced retirement benefit amount, subject to the individual’s actual SSA record and calculation.
Delaying Social Security Until Age 70
Delaying benefits beyond full retirement age can increase the monthly retirement benefit.
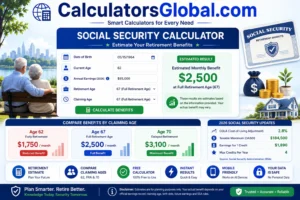
For people born in 1943 or later, the delayed retirement credit is 8% per year for each year of delay after FRA, up to age 70.
For someone with an FRA of 67:
Age 67 → 100%
Age 70 → 124%
SSA’s guidance confirms that someone born in 1960 or later who waits until age 70 receives 124% of their full-retirement-age benefit.
Example
Suppose the full retirement benefit is:
$2,500 per month
A simplified age-70 comparison using 124% would be:
$2,500 × 1.24 = $3,100
This is an illustrative calculation. The actual benefit should be based on the person’s official SSA estimate.
Social Security Calculator by Age
Your claiming age is one of the most important variables in retirement planning.
A calculator can compare:
| Claiming Age | General Effect |
|---|---|
| 62 | Reduced benefit |
| 63–66 | Reduced benefit, depending on birth year |
| FRA | Full retirement benefit |
| 68 | Increased benefit |
| 69 | Higher delayed benefit |
| 70 | Maximum delayed-retirement increase |
After age 70, delaying retirement benefits does not create additional delayed-retirement credits.
Social Security Calculator by Birth Year
Your birth year affects your Full Retirement Age.
For example:
| Birth Year | Full Retirement Age |
|---|---|
| 1943–1954 | 66 |
| 1955 | 66 + 2 months |
| 1956 | 66 + 4 months |
| 1957 | 66 + 6 months |
| 1958 | 66 + 8 months |
| 1959 | 66 + 10 months |
| 1960 or later | 67 |
The birth-year rules are important because claiming-age reductions depend on the number of months between your claiming age and FRA.
Social Security Calculator by Earnings
Your earnings history plays a major role in determining your retirement benefit.
Generally, higher covered earnings can result in a higher Social Security benefit.
However, Social Security does not count unlimited earnings.
In 2026, the maximum amount of earnings subject to Social Security tax is:
$184,500
Earnings above that amount are not subject to Social Security’s OASDI payroll tax and do not increase the Social Security retirement benefit for that year.
Why Earnings History Matters
Suppose two workers have identical birth dates but different lifetime earnings.
Worker A:
Higher covered earnings
Worker B:
Lower covered earnings
Worker A will generally have a higher Social Security retirement benefit.
This is why entering accurate earnings information is important when using a calculator.
Social Security Calculator for Retirement Planning
A Social Security Calculator is only one part of retirement planning.
You should also consider:
- 401(k)
- IRA
- Pension
- Personal savings
- Investments
- Home equity
- Healthcare expenses
- Insurance
- Debt
- Inflation
- Expected retirement expenses
Social Security may provide an important source of retirement income, but many people need additional resources to meet their desired retirement lifestyle.
Social Security Benefits and Work
You can work while receiving Social Security retirement benefits.
However, if you are below full retirement age and earn more than the applicable annual earnings limit, Social Security may withhold part of your benefits.
SSA’s 2026 earnings limits are:
Under FRA for the entire year: $24,480
SSA withholds $1 in benefits for every $2 earned above the limit.
For the year you reach FRA, a higher limit applies to earnings before the month you reach FRA:
$65,160
SSA withholds $1 in benefits for every $3 earned above that limit.
After reaching full retirement age, the earnings test no longer applies.
Social Security Earnings Test
The earnings test is important for people who claim benefits before FRA while continuing to work.
For example, if your earnings exceed the applicable limit, some benefits may be withheld.
However, withheld benefits are not necessarily permanently lost.
SSA states that after reaching full retirement age, benefits can be recalculated to account for months when benefits were withheld because of excess earnings.
This is another reason to use an accurate retirement calculator when deciding when to claim benefits.
Social Security Taxable Maximum
The Social Security taxable maximum is the maximum amount of annual earnings subject to Social Security’s 6.2% employee and employer OASDI tax.
For 2026:
Taxable Maximum = $184,500
The employee Social Security tax rate is:
6.2%
The self-employment Social Security tax rate is:
12.4%
The 2026 Social Security wage base means the maximum employee OASDI tax on covered wages is $11,439.
Medicare taxation is different and does not have the same Social Security taxable maximum.
Social Security Credits
Workers generally need enough Social Security credits to qualify for retirement benefits.
In 2026, workers receive one credit for every:
$1,890 of covered earnings
A person can earn a maximum of:
4 credits per year
The number of credits required depends on the type of benefit.
Why Credits Matter
Credits help determine whether you are insured for certain Social Security benefits.
However, the number of credits does not directly determine the amount of your retirement benefit.
Your benefit amount depends heavily on your earnings history and claiming age.
2026 Social Security Changes
Several important Social Security figures changed for 2026.
The official SSA 2026 fact sheet reports:
| 2026 Social Security Figure | Amount |
|---|---|
| COLA | 2.8% |
| Maximum Taxable Earnings | $184,500 |
| Earnings Needed for One Credit | $1,890 |
| Maximum Credits Per Year | 4 |
| Maximum Benefit at FRA in 2026 | $4,152/month |
| Maximum Benefit at Age 62 in 2026 | $2,969/month |
| Maximum Benefit at Age 70 in 2026 | $5,181/month |
The maximum-benefit examples assume a worker earned the taxable maximum in every year beginning at age 22 and claims benefits at the specified age. Most people will receive less.
Social Security COLA
COLA stands for Cost-of-Living Adjustment.
Social Security benefits are periodically adjusted to account for changes in consumer prices.
For 2026, the Social Security Administration announced a:
2.8% COLA
The estimated average monthly benefit for retired workers increased from approximately:
$2,015 → $2,071
after the 2026 COLA.
Why COLA Matters
COLA helps benefits keep pace with inflation.
However, the actual increase for an individual depends on their existing benefit amount.
A person receiving $1,500 per month will not receive the same dollar increase as someone receiving $3,000 per month.
Social Security Spousal Benefits
Some people may qualify for Social Security benefits based on a spouse’s work record.
Spousal benefits have their own eligibility rules and calculation methods.
A basic retirement calculator focused only on the worker’s earnings may not accurately estimate spousal benefits.
SSA provides specific guidance and benefit tools for people who may qualify as spouses or surviving spouses.
Why Spousal Benefits Need Special Treatment
A person’s own retirement benefit and a potential spousal benefit are not necessarily the same.
The calculation can depend on:
- Age
- Marital status
- Spouse’s benefit
- Claiming age
- Eligibility
- Work history
For a personalized estimate, use official SSA tools.
Social Security Survivor Benefits
Social Security can also provide benefits to eligible survivors.
Potential beneficiaries can include qualifying:
- Spouses
- Children
- Other eligible family members
Survivor benefits have different rules from retirement benefits.
Therefore, a simple retirement calculator should not be used as a complete survivor-benefit calculator.
SSA’s official Online Calculator can provide survivor estimates based on information entered by the user.
Social Security Disability Benefits
Social Security Disability Insurance, or SSDI, is different from retirement benefits.
Eligibility depends on factors including:
- Work history
- Disability requirements
- Insured status
- Earnings history
The amount of a disability benefit can also differ from a retirement benefit.
The SSA’s Online Calculator includes disability estimates based on the information entered.
Social Security Calculator Example
Let’s consider a fictional worker.
Age: 62
Estimated FRA: 67
Estimated FRA Benefit: $2,500/month
Suppose the worker is considering three claiming ages:
| Claiming Age | Example Monthly Benefit |
|---|---|
| 62 | Lower than $2,500 |
| 67 | $2,500 |
| 70 | Higher than $2,500 |
The exact age-62 amount depends on the worker’s birth date and the number of months before FRA.
If the worker is born in 1960 or later, waiting from FRA 67 to age 70 can increase the benefit to 124% of the FRA amount.
Using the $2,500 example:
$2,500 × 124% = $3,100
Again, this is an illustration rather than a personalized SSA estimate.
Social Security Benefit Comparison
A simple conceptual comparison looks like this:
| Claiming Strategy | Monthly Benefit | General Consideration |
|---|---|---|
| Claim at 62 | Lower | Earlier income, permanently reduced benefit |
| Claim at FRA | Full benefit | No early-claiming reduction |
| Delay to 68 | Higher | Fewer years receiving benefits, higher monthly amount |
| Delay to 69 | Higher | Larger monthly benefit |
| Delay to 70 | Highest delayed amount | Maximum delayed-retirement increase |
SSA emphasizes that choosing when to begin benefits is an individual decision involving both advantages and disadvantages.
How to Use a Social Security Calculator
Using an online Social Security Calculator is generally straightforward.
Step 1: Enter Your Birth Date
Your birth date helps determine your retirement-age rules.
Step 2: Enter Your Earnings
Use your actual covered earnings when possible.
Step 3: Enter Expected Future Earnings
If you plan to continue working, estimate future earnings.
Step 4: Select Retirement or Claiming Age
Try multiple scenarios.
For example:
62, 65, 67 and 70
Step 5: Calculate
Review the estimated monthly benefit.
Step 6: Compare Scenarios
Compare the difference between claiming early, at FRA and later.
Step 7: Verify With SSA
For an important retirement decision, compare the calculator result with your official SSA estimate.
The official SSA Online Calculator was updated in August 2026 and allows users to enter earnings and compare benefit estimates.
Common Social Security Calculation Mistakes
Mistake 1: Assuming Everyone Gets the Same Benefit
Social Security benefits vary based on individual earnings history and claiming age.
Mistake 2: Assuming Age 62 Gives Full Benefits
Claiming before FRA can reduce the monthly benefit.
Mistake 3: Ignoring the 35-Year Earnings Rule
Years with no earnings can affect the calculation when a person has fewer than 35 years of covered earnings.
Mistake 4: Assuming Delaying After 70 Increases Benefits
Delayed retirement credits stop accumulating at age 70.
Mistake 5: Using Current Earnings Instead of Lifetime Earnings
Your retirement benefit is not based solely on your current salary.
Mistake 6: Ignoring Future Earnings
If you continue working, additional earnings can potentially replace lower-earning years.
Mistake 7: Treating an Online Estimate as Guaranteed
Future benefit estimates can change because of future earnings, legislation, COLA adjustments and other factors.
Social Security Calculator vs Official SSA Estimate
A third-party Social Security Calculator can be useful for planning and comparison.
However, it may not have access to your official earnings record.
The SSA’s personalized tools can provide estimates using your Social Security earnings information.
SSA’s official Quick Calculator also explains that its estimate is rough because it does not access your personal earnings record.
For important retirement decisions, users should compare any third-party estimate with their official Social Security record.
Tips for Retirement Planning
Check Your Social Security Record
Review your earnings history periodically.
Errors in earnings records can affect future benefit estimates.
Compare Multiple Claiming Ages
Do not look only at age 62.
Compare:
- 62
- 65
- FRA
- 68
- 70
Consider Your Health and Longevity
The financially optimal claiming age can differ from person to person.
Consider Other Income
Include:
- 401(k)
- IRA
- Pension
- Investments
- Savings
- Rental income
- Other retirement income
Plan for Healthcare Costs
Social Security should not be treated as the only source of retirement income.
Consider Inflation
Your future expenses may be higher than today’s expenses.
Review Your Plan Regularly
Retirement planning should be updated as your earnings, savings and circumstances change.
Frequently Asked Questions
What is a Social Security Calculator?
A Social Security Calculator estimates potential Social Security benefits based on information such as earnings history, birth date and claiming age.
How much Social Security will I get?
Your benefit depends on your earnings history, the number of years you worked, your claiming age and other factors. The most accurate personal estimate comes from your official SSA earnings record.
Can I collect Social Security at age 62?
Yes, retirement benefits can generally begin as early as age 62, but claiming before full retirement age results in a reduced monthly benefit.
What is Full Retirement Age?
Full Retirement Age is the age at which you become eligible for your full Social Security retirement benefit. For people born in 1960 or later, it is 67.
What happens if I wait until age 70?
If you delay benefits beyond FRA, your monthly benefit can increase through delayed retirement credits. For people born in 1943 or later, the increase is 8% per year, up to age 70.
Is Social Security based on my last salary?
No. Social Security retirement benefits are based on your covered earnings history rather than simply your final salary.
How many years of earnings are used?
Social Security generally uses your highest 35 years of earnings when calculating retirement benefits. Years without earnings can affect the calculation if you have fewer than 35 years of earnings.
What is the Social Security taxable maximum in 2026?
The 2026 Social Security taxable maximum is $184,500.
What is the Social Security tax rate in 2026?
The Social Security portion of the payroll tax is 6.2% for employees and 6.2% for employers on covered earnings up to the taxable maximum. The self-employment Social Security tax rate is 12.4%.
What is the 2026 Social Security COLA?
The 2026 Social Security COLA is 2.8%.
What is the average Social Security benefit in 2026?
SSA estimates the average monthly Social Security benefit for retired workers at approximately $2,071 in January 2026 after the 2.8% COLA.
What is the maximum Social Security benefit in 2026?
For someone who earned the taxable maximum beginning at age 22, the maximum monthly retirement benefit in 2026 is $2,969 at age 62, $4,152 at full retirement age, or $5,181 at age 70. Most people receive less.
Can I work while receiving Social Security?
Yes. However, before full retirement age, earnings above the applicable annual limit can result in some benefits being withheld. After reaching FRA, the earnings test no longer applies.
Can working longer increase Social Security benefits?
It can. Additional earnings may replace lower-earning years in the highest-35-years calculation, potentially increasing your benefit.
Does Social Security increase with inflation?
Social Security benefits receive cost-of-living adjustments. For 2026, the COLA is 2.8%.
Is the Social Security Calculator accurate?
A calculator can accurately perform the calculation based on the information provided, but an estimate may differ from your official benefit because your actual SSA earnings record, future earnings and applicable rules may differ.
Where can I get my official Social Security estimate?
You can use your personal my Social Security account to view personalized benefit estimates based on your earnings record. SSA also provides its own online calculators.
Should I claim Social Security at 62 or 70?
There is no universal answer. Claiming earlier provides income sooner but reduces the monthly benefit, while delaying can increase the monthly benefit. Your health, longevity, financial needs, spouse’s benefits, taxes and other retirement income should be considered.
Important Social Security Calculator Disclaimer
Social Security benefit estimates are for educational and retirement-planning purposes only.
Actual benefits depend on your official earnings record, birth date, claiming date, future earnings, applicable Social Security rules, cost-of-living adjustments and other factors.
Social Security rules and benefit amounts can change. Always verify important retirement decisions using official information from the Social Security Administration and consider consulting a qualified financial or retirement professional when appropriate.
Conclusion
A Social Security Calculator can be a valuable starting point for retirement planning.
Your potential Social Security benefit depends on several important factors, especially your earnings history, highest 35 years of earnings, birth year, Full Retirement Age and the age at which you begin receiving benefits.
For people born in 1960 or later, Full Retirement Age is 67. Benefits can generally begin at age 62, but claiming early reduces the monthly amount. Waiting beyond FRA can increase benefits through delayed retirement credits, with increases continuing until age 70.
The 2026 Social Security figures also illustrate why keeping the calculator updated is important. The 2026 COLA is 2.8%, the taxable maximum is $184,500, and the maximum benefit for a worker retiring at full retirement age in 2026 is $4,152 per month under the stated maximum-earnings assumptions.
However, the maximum benefit is not a realistic estimate for most workers. Your personal benefit depends on your actual earnings history and claiming strategy.
Use the CalculatorsGlobal.com Social Security Calculator to compare retirement scenarios, estimate potential monthly benefits and understand how claiming age can affect retirement income.
For an important retirement decision, always compare the calculator’s result with your official Social Security estimate.