Estate Tax Calculator to estimate taxable estate, federal estate tax, estate tax exemption and potential tax liability. Learn how estate tax is calculated with examples.A federal Estate Tax Calculator estimates potential estate tax by determining the taxable estate, applying the applicable exclusion amount and calculating the tentative tax before available credits and other adjustments. For 2026, the federal basic exclusion amount is $15 million. Income Tax Calculator — Inheritance Tax Calculator — Percentage Calculator — Compound Interest Calculator — Investment Calculator — Inflation Calculator — Mortgage Calculator — Loan Calculator — Retirement Calculator — Net Worth Calculator
Estate Tax Calculator: Calculate Federal Estate Tax, Taxable Estate & Exemption
Estate Tax Calculator to estimate taxable estate, federal estate tax, estate tax exemption and potential tax liability. Learn how estate tax is calculated with examples.
Estate planning can involve large amounts of money, property, investments and other assets. One of the important questions for families with substantial estates is whether estate tax may apply after someone dies.
An Estate Tax Calculator can help estimate the potential federal estate tax liability based on the value of an estate, applicable deductions, previous taxable gifts and the available estate tax exemption.
In the United States, the federal estate tax is generally based on the value of property transferred at death. However, not every estate owes federal estate tax. The basic exclusion amount is a major factor in determining whether federal estate tax may be due.
For 2026, the IRS states that the federal basic exclusion amount is $15,000,000. The IRS also lists the 2026 estate-tax filing threshold at $15,000,000.
This means an estate below the applicable exclusion amount may generally have no federal estate tax liability, although filing requirements and special circumstances can still matter.
An estate tax calculator can be useful for:
- Estimating potential federal estate tax
- Understanding the estate tax exemption
- Calculating a taxable estate
- Reviewing deductions
- Understanding the impact of lifetime gifts
- Comparing estate values
- Planning for inheritance
- Understanding basic estate-tax concepts
What Is an Estate Tax Calculator?
An Estate Tax Calculator is an online financial planning tool that estimates the potential estate tax associated with transferring assets after death.
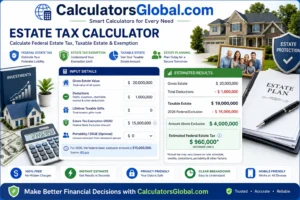
Depending on the calculator, you may enter information such as:
- Total estate value
- Real estate
- Bank accounts
- Investments
- Business interests
- Life insurance
- Retirement accounts
- Other assets
- Debts
- Funeral expenses
- Charitable deductions
- Marital deductions
- Lifetime taxable gifts
- Applicable exemption
The calculator uses these figures to estimate the taxable estate and potential federal estate tax.
What Can an Estate Tax Calculator Show?
A useful calculator may provide:
- Gross estate
- Allowable deductions
- Taxable estate
- Estate tax exemption
- Taxable amount above exemption
- Estimated estate tax
- Remaining estate after estimated tax
The actual federal estate-tax calculation can be more complicated than a simple subtraction because the IRS calculation incorporates taxable gifts, applicable exclusion amounts, credits and other adjustments.
What Is Estate Tax?
Estate tax is a federal tax that may apply to the transfer of property from a deceased person to beneficiaries or other recipients.
The federal estate tax is sometimes called a death tax, although estate tax and inheritance tax are different concepts.
The IRS explains that the federal estate tax is generally calculated by applying the unified rate schedule and then reducing the resulting tax by the available applicable credit.
What Assets Can Be Included?
An estate can potentially include:
- Cash
- Bank accounts
- Stocks
- Bonds
- Real estate
- Businesses
- Vehicles
- Personal property
- Retirement-related assets
- Life insurance interests
- Other property
The exact treatment depends on ownership, beneficiary arrangements and applicable federal law.
Who Pays Estate Tax?
Federal estate tax is generally an obligation associated with the estate, rather than a tax that every beneficiary automatically pays on inherited property.
The executor or personal representative may have responsibilities for determining whether a federal estate tax return is required and, when applicable, filing the return and paying tax from estate assets.
The IRS states that relatively simple estates often do not require an estate tax return, but a return is generally required when the gross estate plus certain adjusted taxable gifts and other specified amounts exceeds the filing threshold for the year of death.
Federal Estate Tax Exemption
The federal estate tax exemption, commonly referred to as the basic exclusion amount, is the amount that can generally be sheltered from federal estate and gift tax under the applicable exclusion system.
The exemption is not a simple deduction applied to the estate in every circumstance. The federal estate and gift tax systems use an applicable exclusion amount and corresponding credit.
For 2026, the IRS states that the basic exclusion amount is:
$15,000,000
This amount applies for calendar year 2026 under current federal law.
Why Is the Exemption Important?
Suppose a person’s applicable taxable estate is below the available federal exclusion amount.
In a simplified example:
Taxable Estate = $10,000,000
2026 Basic Exclusion = $15,000,000
Because the estate is below the basic exclusion amount, the simplified federal estate-tax estimate would be:
$0
However, actual estate-tax obligations can involve other factors, so the calculator should be treated as an estimate rather than a legal determination.
2026 Estate Tax Exemption
For a person dying in 2026, the federal basic exclusion amount is $15 million. The IRS’s current estate-tax information also lists $15 million as the 2026 filing threshold.
| Year of Death | Federal Basic Exclusion Amount |
|---|---|
| 2022 | $12.06 million |
| 2023 | $12.92 million |
| 2024 | $13.61 million |
| 2025 | $13.99 million |
| 2026 | $15.00 million |
The 2026 amount reflects the current federal law and inflation adjustment.
How Estate Tax Is Calculated
A simplified estate-tax calculation can be understood in several stages.
Step 1: Determine the Gross Estate
Add the value of assets included in the estate.
Step 2: Subtract Allowable Deductions
Potential deductions may include qualifying:
- Debts
- Funeral expenses
- Administrative expenses
- Charitable transfers
- Marital transfers
Step 3: Account for Taxable Gifts
Certain lifetime taxable gifts can affect the estate-tax calculation.
The IRS explains that estate and gift taxes use a unified rate structure involving cumulative taxable gifts and the taxable estate.
Step 4: Determine the Applicable Exclusion
Apply the available basic exclusion amount and, where applicable, additional exclusion such as a deceased spouse’s unused exclusion.
Step 5: Calculate Tentative Tax
The federal unified rate schedule is applied to the relevant taxable amount.
Step 6: Apply Available Credits
The applicable credit can reduce the estate tax liability.
This is why an estate-tax calculation is more complex than simply multiplying the estate value by 40%.
Estate Tax Formula
A simplified educational formula is:
Taxable Estate = Gross Estate − Allowable Deductions
Then:
Taxable Amount = Taxable Estate − Available Exclusion
If the taxable amount is zero or negative:
Estimated Federal Estate Tax = $0
If the taxable amount is positive, the applicable federal estate-tax rate schedule and available credits must be considered.
The IRS’s Form 706 instructions explain that the estate tax is calculated using the unified rate schedule and applicable exclusion and credit amounts.
Important
The simplified formula is useful for understanding the concept, but it should not be used as a substitute for completing Form 706 or obtaining professional tax advice for an actual estate.
Gross Estate
The gross estate generally represents the value of property and interests that are included for federal estate-tax purposes before applicable deductions.
Examples may include:
- Real estate
- Cash
- Investment accounts
- Business interests
- Personal property
- Certain insurance interests
- Other assets
Example
Suppose an estate contains:
| Asset | Value |
|---|---|
| Home | $2,000,000 |
| Investment accounts | $4,000,000 |
| Bank accounts | $1,000,000 |
| Business interest | $3,000,000 |
| Other property | $500,000 |
| Gross Estate | $10,500,000 |
The gross estate in this example is $10.5 million before considering deductions and other adjustments.
Taxable Estate
The taxable estate is generally determined after applying qualifying deductions and adjustments to the gross estate.
For example:
Gross Estate = $18,000,000
Allowable Deductions = $2,000,000
Then:
Taxable Estate = $16,000,000
The available exclusion would then be considered.
For 2026:
Basic Exclusion = $15,000,000
A simplified calculation would leave:
$16,000,000 − $15,000,000 = $1,000,000
This does not mean the final federal estate tax is automatically $400,000 because the actual federal calculation includes the unified rate schedule, credits, taxable gifts and other factors.
Estate Tax Deductions
Deductions can reduce the amount subject to federal estate tax.
Potential deductions can include:
- Mortgages and debts
- Funeral expenses
- Administration expenses
- Charitable deductions
- Marital deductions
- Certain taxes
The exact eligibility and calculation depend on federal estate-tax rules.
Why Deductions Matter
Consider:
Gross Estate = $20 million
If qualifying deductions total:
$3 million
Then the simplified taxable estate is:
$17 million
This is lower than the original gross estate.
Marital Deduction
The federal estate tax system generally provides a marital deduction for qualifying property transferred to a surviving spouse.
This can significantly affect estate-tax planning for married couples.
However, special rules can apply, particularly when the surviving spouse is not a U.S. citizen.
Certain transfers to a non-U.S.-citizen spouse may require special planning or use of a Qualified Domestic Trust (QDOT) to obtain certain tax benefits.
For an actual estate plan, professional advice is strongly recommended.
Charitable Deduction
Qualifying transfers to charities can potentially reduce the taxable estate.
For example, if an estate makes a qualifying charitable transfer:
Estate = $20 million
Qualifying charitable deduction = $2 million
Then, subject to the applicable rules:
Adjusted Estate = $18 million
Charitable deductions can therefore play an important role in estate planning.
Lifetime Gifts and Estate Tax
The federal gift and estate tax systems are connected.
Certain taxable gifts made during a person’s lifetime can affect the amount of exclusion available at death.
The IRS describes the estate and gift tax as using a unified rate schedule for cumulative taxable gifts and the taxable estate.
For 2026, the IRS also states that the annual gift tax exclusion is $19,000 per recipient.
The annual gift exclusion and the lifetime basic exclusion are different concepts.
Annual Gift Exclusion vs Lifetime Exclusion
| Feature | Annual Gift Exclusion | Lifetime Basic Exclusion |
|---|---|---|
| Purpose | Certain gifts during life | Lifetime/death transfer system |
| 2026 amount | $19,000 per recipient | $15,000,000 |
| Applies to | Qualifying gifts | Unified gift and estate tax system |
| Same thing? | No | No |
The $19,000 annual exclusion should not be confused with the $15 million basic exclusion amount.
Estate Tax vs Inheritance Tax
Estate tax and inheritance tax are not the same.
Estate Tax
Estate tax is generally imposed on the estate or transfer at death before assets are distributed.
Inheritance Tax
Inheritance tax, where applicable, is generally imposed on the person receiving inherited property.
The United States has a federal estate tax but does not impose a general federal inheritance tax.
Some states have their own estate or inheritance taxes.
This means you should distinguish between:
Federal Estate Tax
and
State Estate/Inheritance Tax
Federal Estate Tax vs State Estate Tax
Federal estate tax is administered by the IRS.
State estate taxes are determined by individual state laws.
A person could potentially have no federal estate tax but still need to consider a state-level estate or inheritance tax depending on the state and circumstances.
Therefore, an online Estate Tax Calculator should clearly state whether it calculates:
- Federal estate tax
- State estate tax
- Both
For CalculatorsGlobal.com, I recommend making the calculator specifically labeled “Federal Estate Tax Calculator” if it only calculates the U.S. federal system.
Estate Tax Calculator Example
Let’s consider a simplified example.
Example: $10 Million Estate
Suppose:
Gross Estate = $10,000,000
Deductions = $500,000
Then:
Taxable Estate = $9,500,000
2026 basic exclusion:
$15,000,000
Since:
$9.5 million < $15 million
the simplified federal estate-tax estimate is:
$0
The IRS’s 2026 exclusion amount is $15 million.
This does not necessarily mean that no estate-tax return or other filing could ever be required; special circumstances can affect filing requirements.
Estate Tax Calculation for a $20 Million Estate
Consider:
Gross Estate = $20,000,000
Deductions = $1,000,000
Simplified taxable estate:
$20,000,000 − $1,000,000 = $19,000,000
2026 basic exclusion:
$15,000,000
Simplified amount above exclusion:
$19,000,000 − $15,000,000 = $4,000,000
This $4 million is not automatically the final tax bill.
The actual federal calculation uses the applicable rate schedule, applicable credit, prior taxable gifts and other adjustments.
Estate Tax Calculation for a $30 Million Estate
Suppose:
Gross Estate = $30,000,000
Allowable Deductions = $3,000,000
Then:
Taxable Estate = $27,000,000
2026 basic exclusion:
$15,000,000
Simplified amount above exclusion:
$27,000,000 − $15,000,000 = $12,000,000
Again, this $12 million represents the amount above the basic exclusion in this simplified example, not the final estate-tax liability.
An actual Form 706 calculation is more detailed.
Estate Tax and Married Couples
Estate planning can be particularly important for married couples.
A surviving spouse may potentially benefit from portability of a deceased spouse’s unused exclusion, commonly called DSUE — deceased spousal unused exclusion.
The IRS explains that an estate may elect to transfer an unused exclusion amount to the surviving spouse under applicable rules.
Simple Example
Suppose:
Spouse A’s exclusion = $15 million
Spouse A’s estate only uses:
$5 million
Potential unused exclusion:
$10 million
If the applicable requirements are met and portability is properly elected, that unused amount may potentially be available to the surviving spouse.
This is a simplified example and actual DSUE calculations can be more complicated.
Portability and DSUE
DSUE stands for Deceased Spousal Unused Exclusion.
It can allow a surviving spouse to use certain unused federal estate and gift tax exclusion from a deceased spouse.
Portability is not automatic in every situation.
An estate generally needs to file the appropriate estate tax return and make the required election.
The IRS Form 706 instructions provide details regarding DSUE and the applicable exclusion amount.
Estate Tax for Non-U.S. Citizens
Estate tax rules can be significantly different for:
- U.S. citizens
- U.S. residents
- Nonresident noncitizens
For nonresident noncitizens, U.S.-situated property and treaty provisions can create different rules.
The IRS provides a separate Form 706-NA for certain nonresident noncitizen estates.
Therefore, a standard estate-tax calculator designed for U.S. citizens should clearly state its assumptions.
Estate Tax Filing Requirements
Not every estate must file a federal estate tax return.
For 2026, the IRS lists $15 million as the filing threshold.
However, filing can also be relevant for reasons such as:
- Portability
- DSUE election
- Certain lifetime gifts
- Special estate circumstances
Therefore:
No estate tax due ≠ necessarily no filing requirement
This distinction is important when designing an Estate Tax Calculator.
Form 706
Form 706 is the United States Estate (and Generation-Skipping Transfer) Tax Return.
It is used to report the estate and calculate federal estate and generation-skipping transfer tax where applicable.
The IRS Form 706 instructions contain the federal rate schedule, exclusion calculations, DSUE provisions and other computation details.
An online calculator should not be presented as a replacement for Form 706.
Estate Tax Rates
The federal estate and gift tax system uses a graduated unified rate schedule.
The IRS Form 706 instructions show rates beginning at 18% and increasing through the schedule to the highest rate of 40%.
It is therefore inaccurate to simply say:
“Estate tax is always 40%.”
The 40% rate is the highest federal estate and gift tax rate, while the actual tax calculation involves the applicable rate schedule and available credit.
Estate Tax Calculation Summary
| Step | Calculation |
|---|---|
| 1 | Determine gross estate |
| 2 | Add relevant taxable gifts/adjustments |
| 3 | Subtract qualifying deductions |
| 4 | Determine taxable estate |
| 5 | Determine applicable exclusion |
| 6 | Calculate tentative tax |
| 7 | Apply applicable credit |
| 8 | Determine estimated estate tax |
This is an educational summary rather than a complete Form 706 worksheet.
How to Use an Estate Tax Calculator
Using an online calculator should be simple.
Step 1: Enter Estate Value
Enter the estimated total value of assets.
Example:
$20,000,000
Step 2: Enter Debts and Deductions
Add applicable:
- Mortgage
- Debts
- Funeral expenses
- Administrative expenses
- Charitable deductions
- Marital deductions
Step 3: Enter Taxable Gifts
If applicable, enter relevant lifetime taxable gifts.
Step 4: Enter Spousal Information
If the calculator supports portability, provide relevant information about the deceased spouse’s unused exclusion.
Step 5: Select Year of Death
The exclusion amount can change by year.
For 2026, the federal basic exclusion is $15 million.
Step 6: Calculate
The calculator estimates:
- Taxable estate
- Applicable exclusion
- Amount subject to tax
- Estimated estate tax
Step 7: Review the Result
Use the result as an estimate and consult a qualified professional for an actual estate.
Estate Planning Considerations
Estate tax planning can involve much more than simply calculating the value of an estate.
Important considerations may include:
- Asset ownership
- Beneficiary designations
- Trusts
- Life insurance
- Charitable giving
- Lifetime gifts
- Business interests
- Real estate
- Marital planning
- State taxes
- Estate liquidity
Estate Liquidity
An estate may be valuable on paper but may not have enough liquid assets to pay taxes and expenses.
For example, an estate could contain:
$20 million in real estate
but only:
$500,000 in cash
Liquidity planning can therefore be important.
Business Interests
Privately owned businesses can make estate valuation more complicated.
Business valuation may require professional appraisal and specialized tax analysis.
Life Insurance
Life insurance can be an important estate-planning tool, but whether insurance proceeds are included in the gross estate can depend on ownership and other circumstances.
Common Estate Tax Mistakes
Mistake 1: Assuming Every Estate Pays Estate Tax
Most estates do not automatically owe federal estate tax.
Mistake 2: Confusing Estate Tax With Inheritance Tax
They are different taxes.
Mistake 3: Using the Wrong Exemption Year
The exclusion amount can change over time.
Mistake 4: Ignoring Lifetime Gifts
Certain taxable gifts can affect the estate-tax calculation.
Mistake 5: Assuming $15 Million Means No Filing Is Ever Required
Filing requirements can involve portability and other circumstances.
Mistake 6: Assuming Estate Tax Is Simply 40%
The federal system uses a unified rate schedule and applicable credit.
Mistake 7: Ignoring State Taxes
Some states impose their own estate or inheritance taxes.
Mistake 8: Treating an Online Calculator as Legal Advice
A calculator provides an estimate and should not replace professional estate-tax advice.
Estate Tax Comparison Table
| Estate Value | Simplified 2026 Basic Exclusion | Amount Above Exclusion* |
|---|---|---|
| $5 million | $15 million | $0 |
| $10 million | $15 million | $0 |
| $15 million | $15 million | $0 |
| $20 million | $15 million | $5 million |
| $25 million | $15 million | $10 million |
| $30 million | $15 million | $15 million |
| $40 million | $15 million | $25 million |
| $50 million | $15 million | $35 million |
*This is a simplified comparison against the 2026 basic exclusion and is not the final federal estate-tax liability. Actual calculations can involve deductions, taxable gifts, applicable credit, DSUE and other adjustments.
Frequently Asked Questions
What is an Estate Tax Calculator?
An Estate Tax Calculator is an online tool that estimates potential estate tax based on estate value, deductions, applicable exclusion and other relevant information.
What is the federal estate tax exemption for 2026?
For 2026, the federal basic exclusion amount is $15 million.
What is the estate tax rate?
The federal estate and gift tax rate schedule ranges from 18% to a maximum rate of 40%.
Does every estate have to pay federal estate tax?
No. Many estates fall below the applicable federal exclusion amount and do not owe federal estate tax.
Does every estate have to file Form 706?
No. Filing requirements depend on the value of the estate and other circumstances. Portability can also make filing relevant even where no estate tax is otherwise due.
What is the 2026 estate tax filing threshold?
The IRS lists the 2026 federal estate-tax filing threshold as $15 million.
Is estate tax the same as inheritance tax?
No. Estate tax generally applies to the estate or transfer at death, while inheritance tax generally applies to the recipient where such a tax exists.
Does the United States have a federal inheritance tax?
The U.S. federal government has a federal estate tax rather than a general federal inheritance tax.
Can married couples combine their estate tax exemptions?
Potentially. Portability can allow a surviving spouse to use a deceased spouse’s unused exclusion if the applicable requirements and election are satisfied.
What does DSUE mean?
DSUE means Deceased Spousal Unused Exclusion. It refers to certain unused federal estate and gift tax exclusion that may be available to a surviving spouse through portability.
Are lifetime gifts included in estate tax calculations?
Certain lifetime taxable gifts can affect the unified estate and gift tax calculation.
What is the difference between gross estate and taxable estate?
Gross estate generally represents property included before deductions, while taxable estate is determined after applicable deductions and adjustments.
Are debts deducted from an estate?
Certain qualifying debts can generally be considered in determining the taxable estate, subject to federal requirements.
Can charitable donations reduce estate tax?
Qualifying charitable transfers can potentially qualify for a charitable deduction and reduce the taxable estate.
Does estate tax apply to real estate?
Real estate can be part of the gross estate, depending on ownership and applicable rules.
Does life insurance count toward an estate?
Life insurance can be included in an estate in certain circumstances, particularly depending on ownership and control of the policy.
What happens if my estate is worth less than $15 million?
For a simple 2026 federal example, an estate below the $15 million basic exclusion generally would not have federal estate tax liability solely because of its value. Other filing or tax considerations may still apply.
What happens if my estate is worth more than $15 million?
An estate above the basic exclusion may have potential federal estate-tax exposure, but the final amount depends on deductions, taxable gifts, applicable credit, portability and other factors.
Is the $15 million exemption per person?
The federal basic exclusion amount is generally associated with an individual. Married couples may potentially use portability to transfer unused exclusion between spouses when the applicable requirements are met.
Can non-U.S. citizens use the $15 million exclusion?
Not necessarily. Different rules can apply to nonresident noncitizens, particularly for U.S.-situated assets. The IRS has separate rules and Form 706-NA for certain nonresident noncitizen estates.
Is an Estate Tax Calculator accurate?
It can accurately perform the assumptions and formulas programmed into it, but an online estimate may not reflect every fact or legal issue affecting an actual estate.
Should I use an Estate Tax Calculator for legal planning?
It is useful for preliminary estimates, but significant estates should be reviewed with a qualified estate-planning attorney, CPA or tax professional.
Important Estate Tax Disclaimer
The Estate Tax Calculator is provided for general educational and estimation purposes only. Federal estate-tax calculations can involve complex rules concerning property valuation, deductions, taxable gifts, trusts, marital transfers, portability, credits, nonresident estates and state-level taxes.
The calculator should not be treated as legal, tax or financial advice and should not replace Form 706 or professional advice.
Federal tax rules can change. Always verify the applicable rules and thresholds with the IRS and a qualified tax professional before making an estate-planning decision.
Conclusion
An Estate Tax Calculator can make a complicated topic easier to understand by showing how estate value, deductions, lifetime gifts and the federal estate-tax exclusion interact.
For 2026, the federal basic exclusion amount is $15 million, according to the IRS.
The most important concepts to understand are:
- Gross estate
- Taxable estate
- Basic exclusion amount
- Estate-tax deductions
- Lifetime taxable gifts
- Applicable credit
- Marital deduction
- Charitable deduction
- Portability
- DSUE
- Federal estate tax
- State estate and inheritance taxes
A simple calculation can provide a useful starting point, but actual estate-tax planning is much more detailed.
For example, a $20 million estate does not simply mean that $5 million is automatically taxed at 40%. The federal estate-tax system uses a unified rate schedule and applicable credit, while deductions, previous gifts and portability can significantly change the result.
Use the CalculatorsGlobal.com Estate Tax Calculator to estimate your potential federal estate-tax exposure and better understand the numbers involved in estate planning.